Banking sector keeps its balance in 1HCY26

MG News | September 18, 2026 at 04:12 PM GMT+05:00

September 18, 2026 (MLN): The commercial banking
sector showed stable performance in the first half of calendar year 2026, as it
continued to demonstrate financial resilience despite shifting interest rate
dynamics and operational cost pressures.
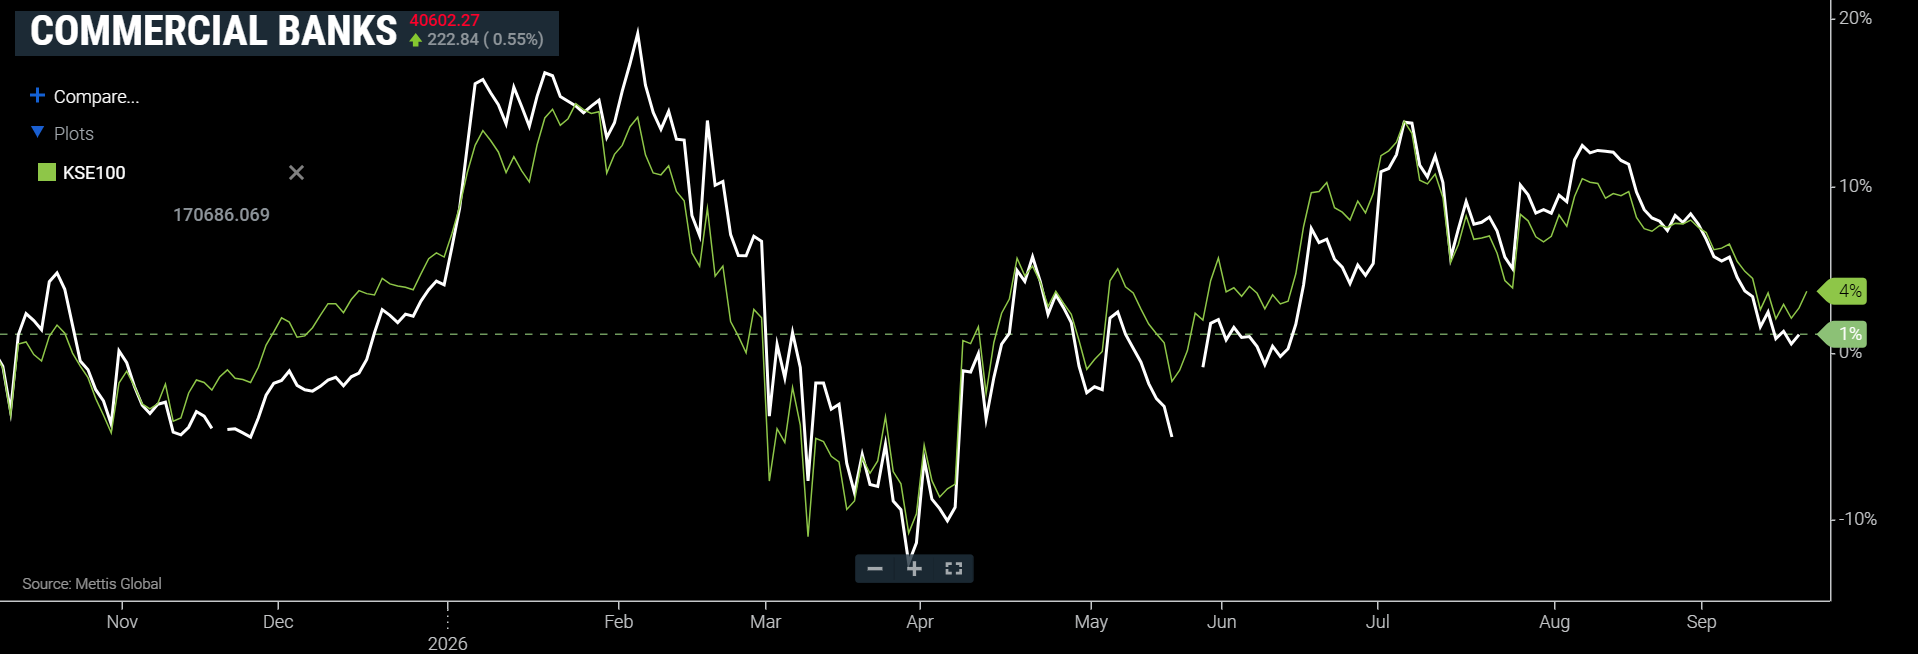
The 13 listed commercial banks covered recorded a 4% YoY
growth in net profits, which clocked in at Rs332bn as against Rs320bn in the
same period last year (1HCY25).
UBL, MEBL, and HBL collectively represented 50% of the
covered banking sector's total profitability in 1HCY26.
UBL stood out as the leading contributor, accounting for
26% (Rs85.0bn) of total sector earnings. MEBL contributed 15% (Rs48.9bn) to
sector profits, while HBL rounded out the top three, accounting for 10%
(Rs33.5bn) of sector earnings.
Conversely, NBP saw its half-year earnings drop 25% YoY
to Rs32.4bn, while SCBPL recorded a 29% drop in net profits to Rs11.8bn.
Fiscal year 2026 has so far remained largely
conservative on the economic front, with GDP growth recovering to 3.7% the
highest in four years while structural reforms under International Monetary
Fund (IMF) programs led to widespread impact.
As per the results compiled of the income statements of
the thirteen commercial banks tracked by Mettis Global (comprising ABL, AKBL,
BAHL, BAFL, FABL, HBL, HMB, MCB, MEBL, NBP, BOP, SCBPLB, and UBL), the sector
saw a growth of 4% YoY in its interest earned, worth Rs2,743.3bn as compared to
Rs2,637.3bn in SPLY.
United Bank Limited remained the market leader in
revenue generation, contributing 24% of total sector turnover with interest
earned of Rs665.0bn, while National Bank of Pakistan and Habib Bank Limited
followed with 13% (Rs361.7bn) and 13% (Rs348.5bn) shares respectively.
Non-markup income channels provided significant momentum
to overall revenue.
Fee and commission income rose 11% YoY to Rs134.2bn,
while foreign exchange (FX) income registered a sharp surge of 40% YoY,
climbing to Rs68.9bn. Driven by these non-markup streams, total income expanded
6% YoY to Rs1,296.9bn.
On the cost front, interest expenses grew by 7% YoY to
Rs1,755.3bn, which compressed the net interest income by 1% YoY to Rs988.0bn in
1HCY26.
On the expense side, the sector's operating expenses
rose 16% YoY to Rs595.2bn. Habib Bank Limited accounted for the largest share
of operating expenses at Rs93.2bn (16% of sector total), followed by United
Bank Limited at Rs84.1bn (14% of sector total).
The sector's profit before tax fell by 2% YoY and stood
at Rs694.1bn as compared to Rs706.0bn in SPLY.
On the tax front, the sector paid lower tax worth
Rs362.3bn against the Rs385.9bn paid in the corresponding period of last year,
depicting a drop of 6% YoY.
Banking Sector’s Financial Highlights (Rupees in Bn)
|
Line Item |
1HCY26 |
1HCY25 |
% Change |
|
Interest Earned |
2,743.30 |
2,637.33 |
4% |
|
Interest Expense |
(1,755.28) |
(1,643.60) |
7% |
|
Net Interest Income |
988.03 |
993.73 |
-1% |
|
Fee and commission |
134.23 |
120.41 |
11% |
|
FX income |
68.90 |
49.27 |
40% |
|
Total Income |
1,296.88 |
1,226.38 |
6% |
|
Operating expenses |
(595.20) |
(512.19) |
16% |
|
Profit Before Tax |
694.10 |
706.04 |
-2% |
|
Taxation |
(362.30) |
(385.86) |
-6% |
|
Profit After Tax |
331.80 |
320.18 |
4% |
Outlook
Pakistan’s economic outlook remains cautiously
optimistic, supported by improving macroeconomic fundamentals, continued
engagement with the International Monetary Fund (IMF), and the government’s
commitment to structural reforms.
A relatively stable exchange rate, strengthening foreign
exchange reserves reaching $22 billion, and sustained inflows of workers’
remittances reaching $41.6 billion provide a foundation for economic
resilience.
Real GDP growth is projected to pick up further to 4.0%
in FY2027, while average inflation is projected at 8.2%, creating room for
eventual monetary recalibration.
"While ongoing geopolitical tensions in the Middle
East present potential challenges, including market volatility and inflationary
pressures, the Bank’s robust capital base, prudent risk management, and
diversified operations position it to maintain resilience," said Meezan
Bank Limited (PSX: MEBL).
The bank noted that its strategy is centered on
achieving balanced and sustainable growth, enhancing digital customer
acquisition, and advancing the transformation towards a fully Shariah-compliant
financial system.
However, energy costs and global commodity price
fluctuations remain key variables affecting overall economic activity.
Escalation in geopolitical tensions in the Middle East,
high fuel costs, and potential choking of critical maritime routes may exert
upward pressure on headline inflation.
National Bank of Pakistan (PSX: NBP) stated that the
operating environment is expected to become increasingly activity-driven and
market-driven rather than predominantly rate-driven.
"With the major phase of monetary easing largely
behind us, earnings dynamics will increasingly depend on the pace of credit
recovery, deposit mobilisation, investment portfolio optimisation, and the
performance of capital and fixed-income markets," the bank noted.
Meanwhile, Habib Bank Limited (PSX: HBL) projected a
positive outlook supported by robust remittance inflows and adherence to the
IMF-supported reform programme.
The bank highlighted its focus on expanding its digital
presence and international footprint, stating: "The policy outlook will
largely depend on the trajectory of inflation, global commodity prices, and
external sector developments, with policymakers continuing to prioritize
macroeconomic stability".
Similarly, The Bank of Punjab (PSX: BOP) highlighted that against this backdrop, the banking sector is well positioned to benefit from strong deposit growth and stable yields, while credit expansion will be supported by improving private sector confidence.
Copyright Mettis Link News
Related News


| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 167,089.28 109.91M | -0.21% -352.63 |
| ALLSHR | 101,117.40 308.32M | -0.15% -155.10 |
| KSE30 | 49,841.71 50.59M | -0.28% -142.15 |
| KMI30 | 240,372.43 78.75M | -0.02% -45.72 |
| KMIALLSHR | 65,518.16 188.07M | -0.05% -35.70 |
| BKTi | 46,228.77 7.60M | -0.60% -281.04 |
| OGTi | 33,974.66 4.20M | -0.27% -91.31 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 82,790.00 | 83,705.00 81,750.00 | 840.00 1.03% |
| BRENT CRUDE | 104.08 | 104.14 102.33 | -0.20 -0.19% |
| RICHARDS BAY COAL MONTHLY | 128.50 | 0.00 0.00 | 0.75 0.59% |
| ROTTERDAM COAL MONTHLY | 143.40 | 143.40 143.40 | -1.15 -0.80% |
| USD RBD PALM OLEIN | 1,167.50 | 1,167.50 1,167.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 91.55 | 91.76 90.01 | 0.06 0.07% |
| SUGAR #11 WORLD | 20.30 | 20.44 20.10 | 0.15 0.74% |
Chart of the Day
Latest News
Top 5 things to watch in this week
 PIB Auction
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|