Weekly Market Roundup
MG News | October 10, 2026 at 12:53 AM GMT+05:00

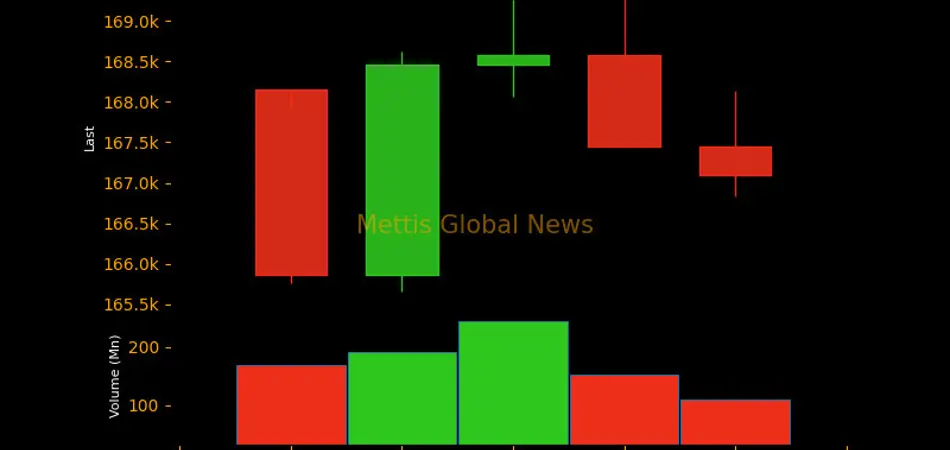
October 10, 2026 (MLN): The benchmark KSE-100 Index closed
the week ended October 9, 2026, at 167,089.28 points, losing 1,066.21 points,
or 0.63% week-on-week, from 168,155.49 points recorded on October 2, 2026.
The market remained under pressure despite
Pakistan’s staff-level agreement with the International Monetary Fund
(IMF), as renewed regional tensions and persistent political uncertainty
dampened investor sentiment and kept buying activity subdued at the Pakistan
Stock Exchange.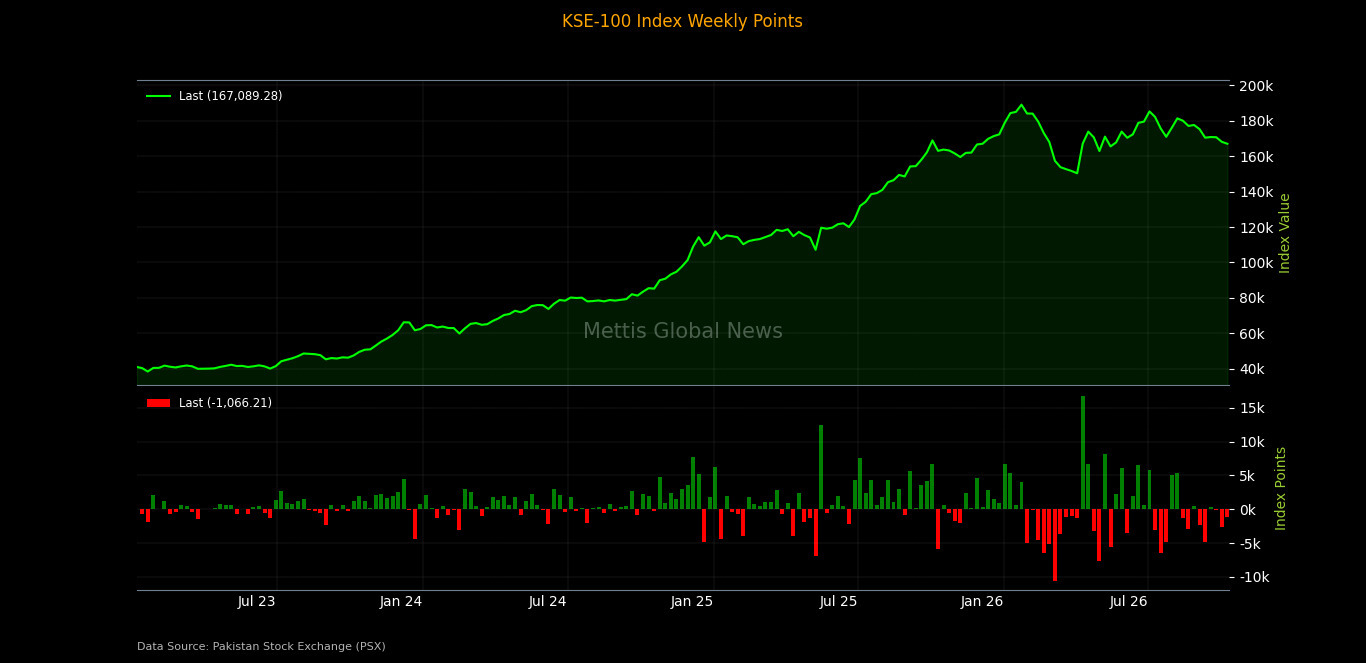
Market Capitalization
The Pakistan Stock Exchange's market capitalization declined
to Rs4.717 trillion during the week, compared with Rs4.753tr on October 2,
2026, registering a decrease of approximately Rs35.65 billion, or 0.75% WoW.
In dollar terms, market capitalization fell from $17.153bn
to $17.028bn, declining by approximately $124.52 million, or 0.73% WoW.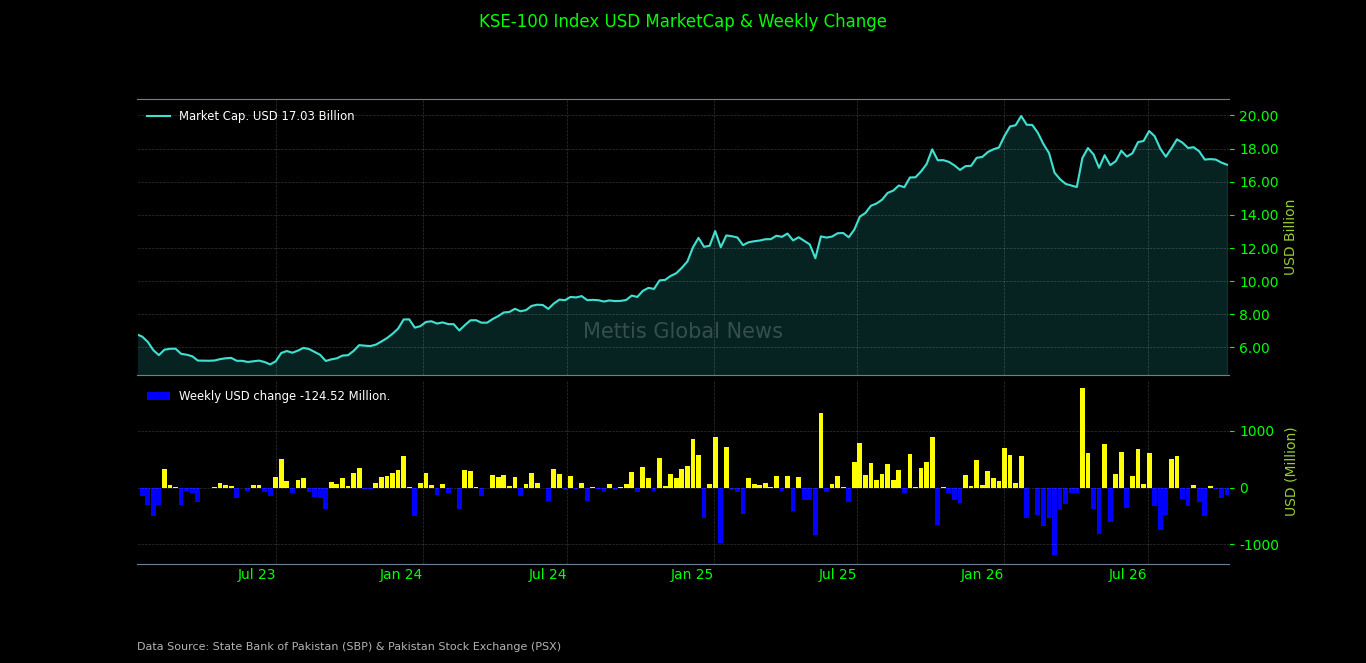
The market's USD-adjusted return stood at -0.61%, compared
with -1.50% in the previous week, showing a relatively smaller decline after
accounting for currency movements._20261009161701404_5eac86.jpeg)
On the macroeconomic front, the State Bank of Pakistan (SBP)
raised Rs376.74bn through the auction of fixed-rate Pakistan Investment
Bonds (PIBs) on October 7, 2026, exceeding the revised target of Rs350bn
against total bids of Rs849.05bn, with the 3-year tenor attracting the highest
acceptance at Rs220.46bn.
Pakistan’s
central government debt rose 7.09% year-on-year to Rs82.95tr in August
2026, compared to Rs77.46tr a year earlier, while declining 0.52%
month-on-month from Rs83.38 trillion in July, according to State Bank of
Pakistan data.
Net savings mobilized through National Savings Schemes (NSS)
increased 11.8% year-on-year to Rs32.8bn in August 2026, but declined 38.4%
month-on-month, while cumulative mobilization during 2MFY27 rose 17% to Rs86bn,
according to data compiled by the State Bank of Pakistan.
Pakistan’s
workers’ remittances declined 1.9% month-on-month to $3.59bn in September
2026 but increased 12.7% year-on-year, with Saudi Arabia remaining the largest
source at $899.1m, according to the State Bank of Pakistan.
Index Movers
Sector-wise performance remained broadly negative during the
week, with Commercial Banks emerging as the largest drag on the KSE-100 Index,
shedding 551.45 points, followed by Fertilizer at 233.58 points, Automobile
Assembler at 96.80 points, Cement at 88.97 points, and Textile Composite at
43.07 points.
Other major negative contributors included Food &
Personal Care Products at 36.52 points, Leather & Tanneries at 27.94
points, Transport at 19.34 points, Investment Banks / Investment Companies /
Securities Companies at 18.32 points, Oil & Gas Exploration Companies at
17.23 points, Paper, Board & Packaging at 17.08 points,
Chemical at 16.07 points, Cable & Electrical Goods at
14.56 points, Sugar & Allied Industries at 12.87 points, Apparel at 11.76
points, Insurance at 10.92 points, Engineering at 10.90 points, Property at
8.09 points, Miscellaneous at 8.05 points, Vanaspati & Allied Industries at
4.98 points, Pharmaceuticals at 3.11 points,
Textile Spinning at 2.60 points, Tobacco at 2.17 points,
Close-End Mutual Funds at 1.78 points, Textile Weaving at 1.19 points,
Automobile Parts & Accessories at 0.82 points, Leasing Companies at 0.73
points, and Woollen at 0.05 points.
On the upside, Oil & Gas Marketing Companies provided
the largest sectoral support, adding 109.55 points, followed by Power
Generation & Distribution at 35.98 points, Real Estate Investment Trust at
19.64 points,
Refinery at 13.86 points, Technology & Communication at
8.78 points, Glass & Ceramics at 6.01 points, Modarabas at 0.90 points, and
Synthetic & Rayon at 0.02 points.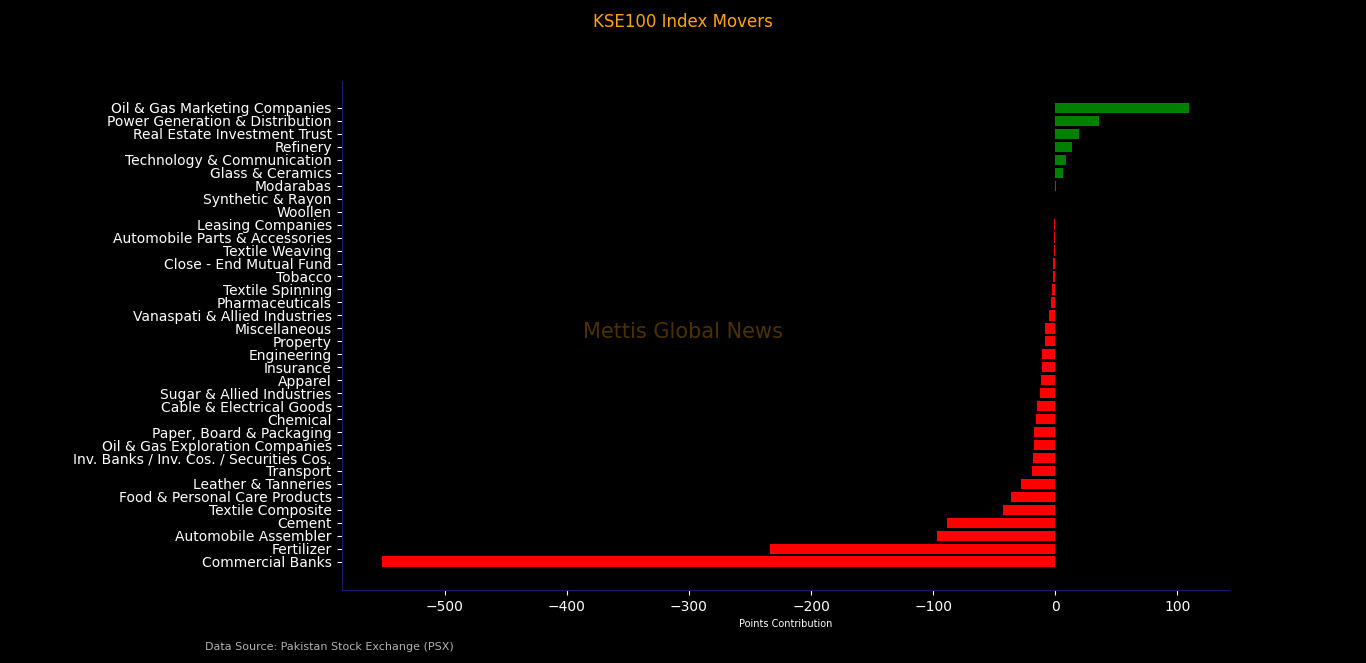
Among individual stocks, PSO emerged as the largest positive
contributor to the index, adding 112.69 points, followed by HUBC at 52.00
points, POL at 46.71 points, ENGROH at 43.80 points, MARI at 33.97 points, FCCL
at 30.08 points, ATRL at 23.59 points, AKBL at 19.08 points, TGL at 15.18
points, BML at 14.40 points,
DCR at 12.79 points, ABL at 12.24 points, TRG at 11.28
points, AGP at 10.93 points, ABOT at 10.81 points, MTL at 10.49 points, GLAXO
at 9.97 points, MLCF at 8.18 points, KEL at 7.82 points,
TPLRF1 at 6.85 points, CHCC at 6.84 points, COLG at 5.61
points, SYS at 5.37 points, HINOON at 4.85 points, PIOC at 1.76 points, LOTCHEM
at 1.75 points, SHFA at 1.55 points, FHAM at 0.90 points, HALEON at 0.17
points, and IBFL at 0.02 points.
On the downside, HBL was the largest drag on the benchmark,
erasing 135.70 points, followed by MCB at 130.88 points, UBL at 121.46 points,
FATIMA at 98.28 points, FFC at 85.26 points, LUCK at 80.61 points, SAZEW at
73.59 points,
NBP at 66.67 points, PSX at 62.12 points, OGDC at 57.15
points, BOP at 41.60 points, PPL at 40.77 points, EFERT at 40.42 points, BAHL
at 40.13 points, NML at 29.63 points, CPHL at 28.70 points, SRVI at 27.94
points, DGKC at 20.86 points,
FABL at 19.76 points, PIBTL at 19.34 points, NPL at 18.38
points, LCI at 17.82 points, PKGS at 17.08 points, GAL at 16.62 points, NATF at
16.01 points, HMB at 14.69 points, PAEL at 14.56 points, THCCL at 13.66 points,
JDWS at 12.87 points,
IMAGE at 11.76 points, KTML at 11.53 points, SEARL at 11.14
points, SCBPL at 10.77 points, KOHC at 10.59 points, BAFL at 10.07 points,
CNERGY at 9.73 points, AHCL at 9.63 points, PSEL at 9.60 points, GHGL at 9.17
points,
MUREB at 8.99 points, ISL at 8.74 points, JVDC at 8.09
points, UPFL at 8.00 points, AIRLINK at 7.22 points, POWER at 7.20 points, INDU
at 7.20 points, FFL at 6.78 points, MEBL at 5.44 points, SSOM at 4.98 points,
HCAR at 4.78 points,
NCPL at 4.65 points, BWCL at 2.91 points, GHNI at 2.73
points, GADT at 2.60 points, SSGC at 2.50 points, ATLH at 2.38 points, NESTLE
at 2.34 points, INIL at 2.17 points, PAKT at 2.17 points, ILP at 1.90 points,
HGFA at 1.78 points,
YOUW at 1.19 points, THALL at 0.82 points, KAPCO at 0.81
points, PGLC at 0.73 points, PTC at 0.65 points, APL at 0.54 points, and SNGP
at 0.09 points. BNWM contributed a negative 0.05 points.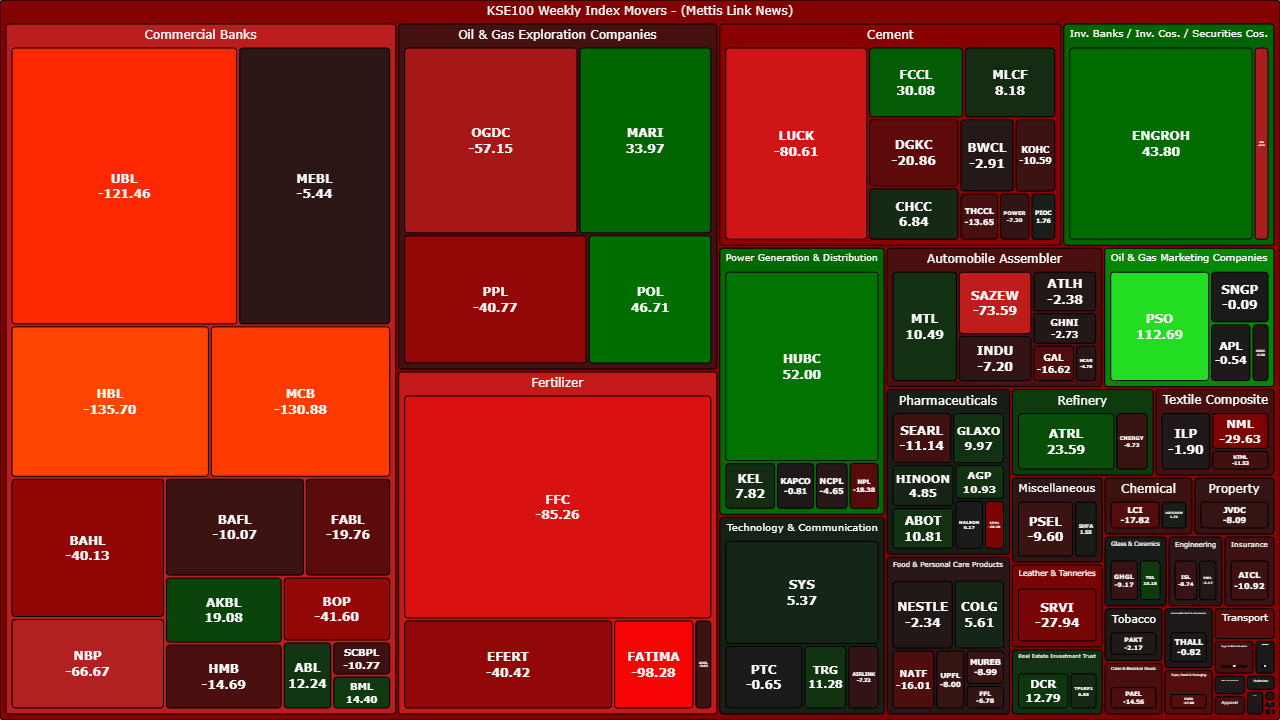
FIPI/LIPI
Foreign investors recorded net equity sales of Rs418.80m
($1.51m) during the week, with net selling by Foreign Corporates outweighing
purchases by Overseas Pakistanis and Foreign Individuals.
Foreign Corporates recorded net equity sales of Rs923.85m
($3.34m), while Overseas Pakistanis remained net buyers with purchases of
Rs504.65m ($1.82m). Foreign Individuals recorded net purchases of Rs0.40m ($1,453).
Including debt flows, foreign investors recorded net sales
of Rs416.97m ($1.51m). Overseas Pakistanis recorded net debt purchases of
Rs1.84m ($6,630), partially offsetting foreign equity outflows.
On the local side, investors recorded net equity purchases
of Rs418.80m ($1.51m), broadly offsetting foreign investors' net equity sales.
Individuals emerged as the largest local equity buyers,
recording net purchases of Rs3.15bn ($11.37m), followed by Companies with
Rs1.80bn ($6.49m), Banks/DFIs with Rs1.20bn ($4.32m), NBFCs with Rs6.15m
($22,209), and Other Organizations with Rs22.60m ($81,603).
Meanwhile, Mutual Funds remained the largest local equity
sellers, with net sales of Rs4.87bn ($17.59m), followed by Insurance Companies
with Rs816.21m ($2.95m) and Broker Proprietary Trading with Rs66.46m
($239,940).
In the debt market, Mutual Funds recorded the largest net
purchases at Rs44.80bn ($161.72m), followed by Other Organizations with
Rs168.51m ($608,335) and Broker Proprietary Trading with Rs0.87m ($3,148).
Meanwhile, Banks/DFIs were the largest debt-market sellers,
recording net sales of Rs44.69bn ($161.35m), followed by Insurance Companies
with Rs164.05m ($592,235), Companies with Rs61.78m ($223,014), Individuals with
Rs47.45m ($171,308), and NBFCs with Rs0.20m ($734).
Overall, foreign investors recorded net sales of Rs416.97m
($1.51m) across equity and debt markets, while local investors recorded net
purchases of approximately Rs416.97m ($1.51m), leaving the combined net flow
close to neutral._20261009161737300_c53cbf.jpeg)
Copyright Mettis Link News
Related News

| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 167,089.28 109.91M | -0.21% -352.63 |
| ALLSHR | 101,117.40 308.32M | -0.15% -155.10 |
| KSE30 | 49,841.71 50.59M | -0.28% -142.15 |
| KMI30 | 240,372.43 78.75M | -0.02% -45.72 |
| KMIALLSHR | 65,518.16 188.07M | -0.05% -35.70 |
| BKTi | 46,228.77 7.60M | -0.60% -281.04 |
| OGTi | 33,974.66 4.20M | -0.27% -91.31 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 82,625.00 | 83,705.00 81,750.00 | 675.00 0.82% |
| BRENT CRUDE | 104.27 | 105.09 102.33 | -0.01 -0.01% |
| RICHARDS BAY COAL MONTHLY | 128.50 | 0.00 0.00 | 0.75 0.59% |
| ROTTERDAM COAL MONTHLY | 143.40 | 143.40 143.40 | -1.15 -0.80% |
| USD RBD PALM OLEIN | 1,167.50 | 1,167.50 1,167.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 91.54 | 92.17 90.01 | 0.05 0.05% |
| SUGAR #11 WORLD | 20.27 | 20.44 20.09 | 0.12 0.60% |
Chart of the Day
Latest News
Top 5 things to watch in this week
 PIB Auction
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|