SBP flags stronger banking resilience, 9.1% balance sheet growth in H1CY26
MG News | September 15, 2026 at 10:08 AM GMT+05:00

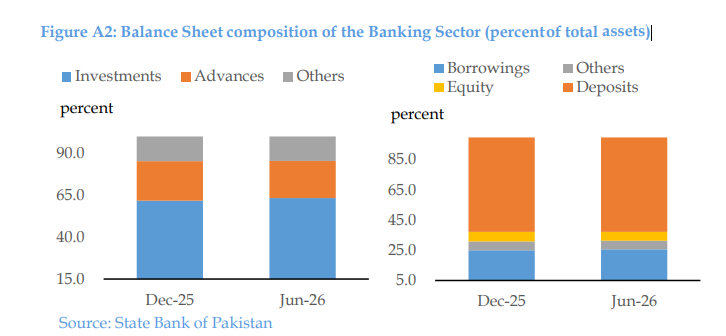
September 15, 2026 (MLN): The State Bank of Pakistan (SBP), in its Mid-Year Performance Review of the Banking Sector for H1CY26, reported that the banking sector's balance sheet expanded by 9.1% to Rs68,997 billion during the period, primarily driven by increased investments in government securities, compared to 11.0% growth in H1CY25.
Investments contributed 79.4% of the balance sheet increase,
while advances contributed 8.7%, pushing the share of investments in total
assets up to 63.3% in June 2026 from 61.8% in December 2025.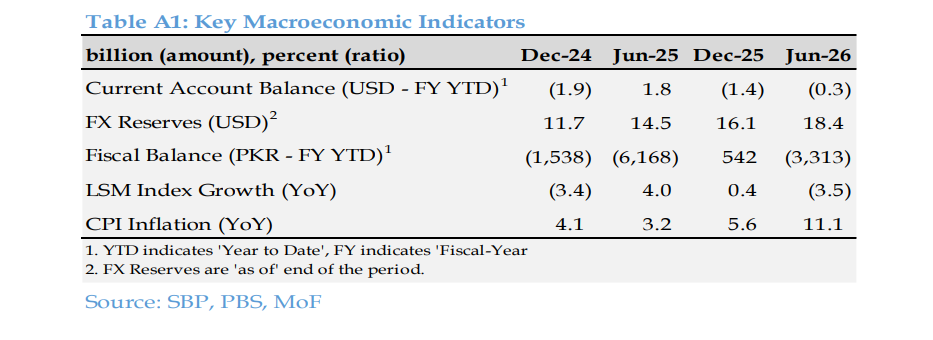
Within government securities, the highest increase came in
Market Treasury Bills (MTBs), followed by Ijara Sukuk and Pakistan Investment
Bonds (PIBs), with MTBs, Ijara Sukuk and PIBs rising by Rs2,943bn, Rs1,255bn
and Rs834bn, respectively.
As a result, the share of MTBs in total government
securities rose to 20.1% in June 2026 from 14.8% in December 2025, while the
PIB share declined to 60.7% from 66.5%.
Gross advances grew by a muted 2.9% during H1CY26, against a
15.2% contraction in H1CY25, with domestic advances up 2.6% and overseas
advances up 6.4%. Private sector advances, which make up 75.4% of total
domestic advances, grew 2.7%.
Within the corporate segment, fixed investment financing
rose by Rs69bn while working capital advances contracted. SME advances, at 7.8%
of total domestic private sector advances, increased by Rs41bn, mainly driven
by long-term financing which grew by Rs77bn.
Consumer financing rose by Rs132bn, led by auto financing (up Rs56 billion) and mortgage financing (up Rs49bn), with mortgage lending gaining further traction on the back of the government's subsidized housing scheme. Public sector advances increased by Rs87bn, mainly on energy sector financing linked to circular debt settlements, which rose by Rs183bn.
On the funding side, banks mobilized additional deposits of
Rs3,673bn (9.3% growth) during H1CY26, against 17.7% growth in H1CY25, driven
mainly by current deposits followed by savings deposits. Borrowings increased
by Rs1,890bn, largely through secured borrowing from SBP.
Islamic Banking Institutions (IBIs) continued to outperform
the conventional sector, growing 13.0% in H1CY26, with their share of total
banking sector assets and deposits rising to 23.7% and 29.2%, respectively.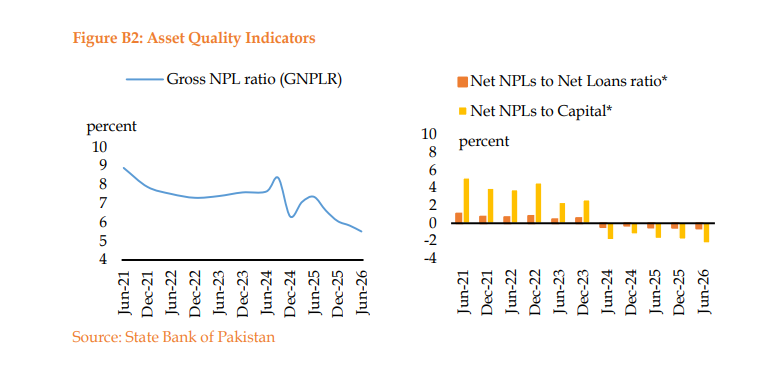
The SBP noted that credit risk did not pose any serious
concerns to financial stability during H1CY26. The gross NPL ratio declined to
5.5% in June 2026 from 6.1% in December 2025, as NPLs fell by Rs62bn against a
Rs460bn rise in gross advances, with the largest reduction coming from
agribusiness and individual borrowers.
The provisioning coverage ratio improved to 110.2% from
107.7%, pushing the net NPLs to net loans ratio to negative 0.6%, while net
NPLs to capital improved to negative 2.3% from negative 1.8%.
Liquidity buffers remained strong, with the liquid assets to
total assets ratio rising to 68.3% from 66.2%, liquid assets to total deposits
up to 108.8% from 105.6%, and liquid assets to short-term liabilities up to
117.0% from 110.8%.
The Liquidity Coverage Ratio (LCR) and Net Stable Funding
Ratio (NSFR) eased slightly to 214.1% and 169.5%, respectively, from 215.0% and
174.3% in December 2025, but remained well above the regulatory threshold of
100%.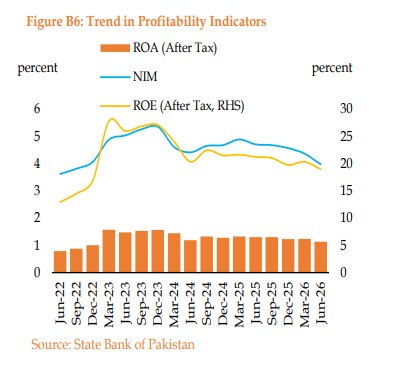
Growth in the sector's earnings remained moderate, with
after-tax profit at Rs370 billion in H1CY26 against Rs365bn in H1CY25.
Net interest income eased to Rs1,140bn from Rs1,157bn on
higher interest expenses following a 100 basis point policy rate hike in April
2026, while non-interest income rose to Rs370bn from Rs289bn, supported by
foreign currency dealing income, gains on sale of securities, and fee and
commission income.
Non-interest expenses rose to Rs753bn from Rs634bn, pushing
the cost-to-income ratio up to 49.9% from 43.9%. As a result, Return on Assets
(ROA) declined to 1.1% from 1.3%, and Return on Equity (ROE) eased to 19.0%
from 21.3%.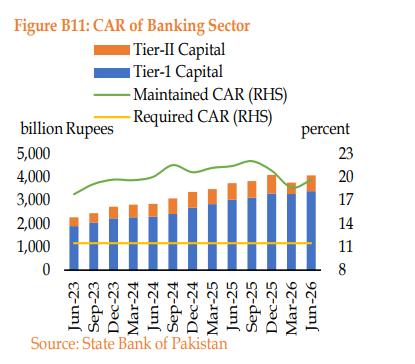
The Capital Adequacy Ratio (CAR) moderated to 19.6% from
20.8% in December 2025, as eligible capital contracted 0.5% while risk-weighted
assets rose 5.8%, partly due to a Rs134bn revaluation deficit on government
securities.
The leverage ratio slipped to 4.4% from 4.6%. Despite the
moderation, the SBP said the sector's solvency position remained strong, and
the latest macro stress tests showed the banking sector, including large
systemically important banks, is expected to remain solvent and resilient, with
the capacity to withstand even severe shocks over the projected two-year
horizon.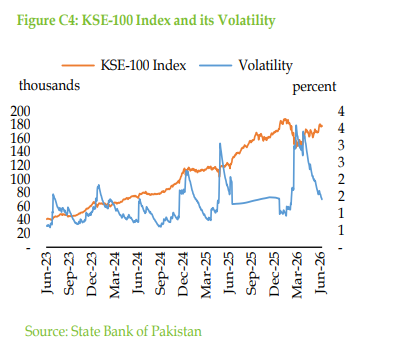
The Review further highlighted increased stress in the
equity market during H1CY26, while conditions in the foreign exchange and money
markets remained relatively calmer.
The KSE-100 index grew 2.5% in H1CY26 versus 38.5% growth in
H2CY25, touching around 190,000 on January 23, 2026 before declining 11.5% to
148,743 between February 7 and March 31, 2026 amid the Middle East conflict.
The index later recovered to 178,415 by end-June 2026, a
19.9% gain in the second quarter, aided by Pakistan's re-entry into
international capital markets, an IMF disbursement of USD1.3 billion, and
bilateral financial arrangements.
The interbank PKR/USD parity averaged Rs279.2 in H1CY26
against Rs281.7 in H2CY25, while SBP's FX reserves rose to $18.4bn by end-June
2026 from $16.1bn in December 2025. In the money market, SBP raised the policy
rate by 100 basis points to 11.5% in April 2026 amid rising inflation, while
average OMO injections rose to Rs2,284bn in H1CY26 from Rs1,877bn in H2CY25.
Meanwhile, the latest Systemic Risk Survey (18th wave,
July-August 2026), which drew a 47% response rate against 45% previously,
identified volatility in commodity prices, including oil, as the top-tier risk,
followed by global geopolitical risks.
Despite these concerns, respondents expressed confidence in
the stability of the financial system and the ability of regulators to ensure
financial stability.
Copyright Mettis Link News
Related News
| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 169,449.43 48.63M | 0.88% 1478.77 |
| ALLSHR | 102,371.35 116.81M | 0.74% 751.47 |
| KSE30 | 50,499.48 16.89M | 0.82% 411.10 |
| KMI30 | 241,619.49 22.67M | 0.69% 1662.39 |
| KMIALLSHR | 66,410.32 77.39M | 0.75% 492.18 |
| BKTi | 47,085.01 4.26M | 0.84% 392.70 |
| OGTi | 34,696.79 2.07M | 0.71% 245.60 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 77,480.00 | 79,110.00 77,350.00 | -1670.00 -2.11% |
| BRENT CRUDE | 107.60 | 107.63 106.25 | 1.92 1.82% |
| RICHARDS BAY COAL MONTHLY | 130.00 | 0.00 0.00 | 3.40 2.69% |
| ROTTERDAM COAL MONTHLY | 140.00 | 0.00 0.00 | 0.95 0.68% |
| USD RBD PALM OLEIN | 1,228.00 | 1,228.00 1,228.00 | 0.00 0.00% |
| CRUDE OIL - WTI | 103.40 | 103.42 101.83 | 2.01 1.98% |
| SUGAR #11 WORLD | 18.16 | 18.39 17.96 | 0.01 0.06% |
Chart of the Day
Latest News
Top 5 things to watch in this week
 Auto Numbers
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|