Pakistan Needs Power Capacity Optimization
Shahid Anwar | September 28, 2026 at 11:39 AM GMT+05:00

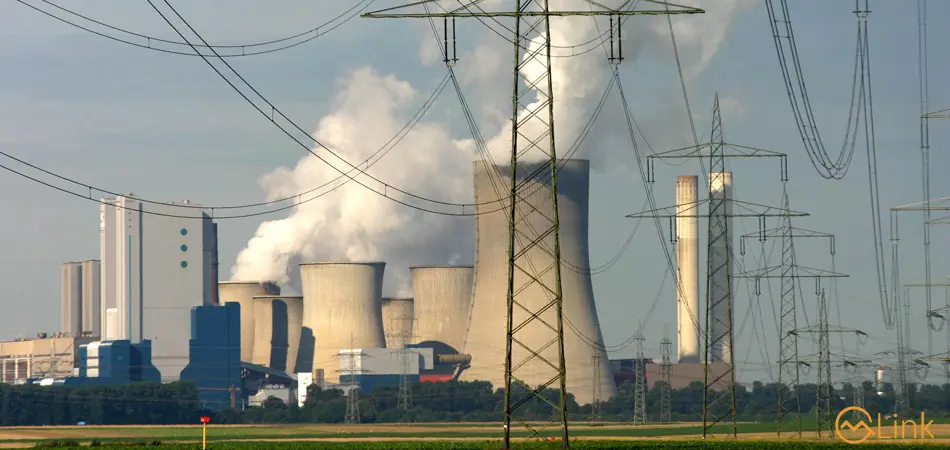
September 28, 2026 (MLN): Pakistan’s power sector no longer faces simply
a shortage of electricity. It now faces a more difficult question: how to get greater value from the generation
capacity it already has.
A significant part of that capacity remains
under-utilized, while consumers continue to bear high electricity costs and the
country still considers additional generation investments.
What Pakistan needs now is a clear assessment of how
much capacity is actually required, what is preventing existing capacity from
being fully utilized and where the real bottlenecks lie.
Paying for Capacity, But Not Using It
According to Ministry of Energy documents, the federal
government paid Rs. 2.935 trillion to independent power producers (IPPs) during
the first 11 months of FY2025-26, covering July 2025 to May 2026. Billing for
June was still incomplete when the figures were compiled.
The Ministry clarified that payments were made at rates approved
by NEPRA or specified in agreements with power producers. [Ministry of Energy, Power Division]
The figure is substantial, but the real issue is not
simply how much Pakistan pays power producers. It is whether the country’s
generation capacity, contractual commitments, transmission network and
electricity demand are properly aligned.
NEPRA’s Performance Evaluation Report for FY2024-25
provides an important indication of the problem. Thermal power plants operated
at an overall utilization rate of 42.5% against reference capacity, while
renewable energy plants averaged 36.6%. NEPRA reported total power purchase
costs of Rs. 2,943.214 billion, excluding electricity imported from Iran.
Of this, 61% was Capacity Purchase Price and 39% Energy
Purchase Price. The average Capacity Purchase Price was Rs. 14.3 per kWh,
compared with Rs. 9.0 per kWh for Energy Purchase Price. NEPRA attributed the
elevated capacity cost mainly to excessive installed capacity and low
utilization of existing plants. [NEPRA, Performance
Evaluation Report of Operational Power Plants FY2024-25]
These figures need to be understood carefully. Capacity
payments are not simply payments for electricity that was never generated.
They are linked
to fixed costs associated with committed generation capacity under contractual
arrangements. Investors made those investments on the basis of contractual
agreements, and legitimate contractual obligations cannot simply be ignored.
But contracts do not eliminate the economic question.
When fixed costs are spread over a smaller volume of electricity because
available capacity is under-utilized, the cost burden on each unit consumed
becomes higher. That can feed into tariffs and weaken the competitiveness of
businesses and industry.
Lower utilization is not caused by weak demand alone.
NEPRA has identified reduced electricity demand, AT&C-based load shedding
and other operational factors affecting thermal plant utilization.
Renewable utilization is also affected by the
availability of natural resources and transmission constraints. The issue,
therefore, is not simply excess generation; it is whether the entire power
system is being planned and operated efficiently. [NEPRA, Performance Evaluation Report of Operational Power Plants
FY2024-25]
This is why Pakistan’s power challenge cannot be reduced
to IPPs alone. Generation, transmission, distribution, demand and contractual
arrangements have to be considered together.
Transmission is particularly important. There is little
economic benefit in having generation capacity available if electricity cannot
reliably reach where it is needed.
The same applies to renewable energy. Adding generation
does not automatically reduce system costs if the transmission network cannot
efficiently evacuate and distribute that power.
From Planning to Capacity Discipline
Pakistan already has institutions responsible for many
of these functions. NEPRA regulates the sector and monitors plant performance
and costs. The Ministry of Energy provides policy direction, while the
Independent System and Market Operator (ISMO) is responsible for system and
market functions.
Pakistan has also moved towards an Integrated System
Plan covering generation and transmission requirements for 2025–35.
The revised Indicative Generation Capacity Expansion
Plan and transmission planning framework form part of the country’s formal
capacity-planning process. [NEPRA;
Ministry of Energy; ISMO]. The gap,
therefore, is not the absence of planning. It is the need for a focused
optimization exercise.
Pakistan should
consider establishing a Power Capacity Optimization Task Force within the existing planning framework.
Its purpose would not be to create another permanent layer of bureaucracy or
duplicate the work of NEPRA, ISMO or the Ministry of Energy. Instead, it should
use the data and findings of existing planning exercises and undertake a
time-bound review focused specifically on getting greater economic value from
capacity already available.
The Task Force should examine, plant by plant, how much
generation capacity exists, how much is actually being utilized, why some
plants remain under-utilized, where transmission and distribution constraints
are limiting dispatch, and what contractual or commercial changes could improve
the economics of the system. It should also establish how much additional
capacity Pakistan genuinely needs after taking existing available capacity and
transmission constraints into account.
This would build on steps the government has already
taken. The Power Division reported that unnecessary power projects with a
combined capacity of 9,500 MW were
cancelled in 2025, while negotiations with IPPs eliminated a cumulative Rs. 3.4 trillion financial burden on
consumers and the national exchequer. The Power Division also reported tariff
reductions resulting from the IPP negotiations. [Ministry of Energy, Power Division, Performance Report 2025]
The lesson should now be institutionalized. Existing IPP
agreements should be examined wherever legally and commercially feasible, with
the objective of better aligning costs with availability, reliability,
performance and actual system requirements. This should not mean undermining
legitimate investor rights. Public-sector generation should face the same
economic test.
Where plants are reliable and economically justified,
they should continue to support the system. Where capacity remains persistently
under-utilized, the reasons should be identified and commercially viable
options considered, including restructuring, conversion, changes in operating
arrangements or retirement where justified.
Before Building More, Use What We Have
Future capacity decisions should also pass a simple
test: Is the additional capacity
genuinely needed, when will it be needed, can the transmission system support
it, and is it the least-cost option? Pakistan’s IMF programme points in
the same direction.
The government committed to carefully reviewing the need
for additional generation capacity and not entering into further capacity
commitments without the necessary transmission infrastructure and full
utilization of existing capacity at peak times. [IMF, First Review under the Extended Fund Facility]
This does not mean Pakistan should stop investing in
electricity generation. Economic growth, industrial expansion and the
transition towards cleaner energy will eventually require additional capacity.
But new investment should follow demonstrated demand rather than create
long-term fixed costs ahead of need.
The demand side is equally important. More competitive
electricity prices, reliable supply and better distribution performance can
encourage industry, agriculture and businesses to use more electricity
productively. If productive consumers reduce their grid consumption because
electricity is too expensive or unreliable, the fixed costs of the system do
not disappear. They have to be recovered from a smaller volume of electricity.
The emerging competitive electricity market could also
help. The transition towards the Competitive Trading and Bilateral Contract
Market is intended to give bulk consumers greater choice in sourcing
electricity, while the system is being introduced in a phased manner. Greater
competition, if implemented transparently and supported by adequate grid
capacity, could improve procurement discipline and give productive consumers
more options. [ISMO; NEPRA; IMF]
The proposed Task Force should therefore produce more
than another government report. Within a defined period, it should publish a Power Capacity Optimization Plan
setting out existing capacity, utilization levels, transmission constraints,
economically justified capacity requirements and a timetable for addressing the
gaps.
The results should be measurable. Consumers should be
able to see how much generation capacity is available, how much is being
utilized, what it costs and why any new capacity is being proposed.
Pakistan has spent years focusing on how to produce more
electricity. The challenge has now changed. The country needs to make better economic use of the capacity it
already has before committing consumers to more long-term costs.
That is not an argument against private investment or
legitimate contractual returns. It is an argument for better planning, stronger
transparency and greater discipline in capacity decisions.
Pakistan already has the institutions, data and planning
mechanisms needed to begin this exercise. What is needed now is to bring them
together around one practical objective: use existing capacity better, remove the constraints that prevent its
utilization, encourage productive electricity demand and add new capacity only
when the need is clearly demonstrated.
A focused Power
Capacity Optimization Task Force could turn that objective into a measurable
programme of action. For Pakistan’s
power sector, the next priority should not simply be adding more capacity, but
getting more value from what the country is already paying for.
About Author:
The writer, Shahid Anwar, is an Economic Analyst and
former Secretary General of the Federation of Pakistan Chambers of Commerce and
Industry (FPCCI).
He also served as Senior Director Research at the
Institute of Cost and Management Accountants of Pakistan (ICMAP), with 36 years
of experience in business, trade and economic affairs. He provides advisory
support on trade, investment and business partnerships.
Disclaimer:
The above analysis/article is for informational and
educational purposes only.
Copyright Mettis Link News
Related News
| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 170,340.13 49.86M | -0.25% -425.09 |
| ALLSHR | 103,068.44 209.60M | -0.17% -172.61 |
| KSE30 | 50,675.67 18.66M | -0.27% -138.22 |
| KMI30 | 243,686.17 28.56M | -0.29% -705.13 |
| KMIALLSHR | 66,775.59 147.37M | -0.23% -152.67 |
| BKTi | 47,115.44 2.74M | -0.34% -158.87 |
| OGTi | 34,936.26 1.21M | -0.21% -73.17 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 83,425.00 | 85,595.00 83,040.00 | -995.00 -1.18% |
| BRENT CRUDE | 106.68 | 107.95 105.06 | 2.36 2.26% |
| RICHARDS BAY COAL MONTHLY | 123.00 | 0.00 0.00 | -0.10 -0.08% |
| ROTTERDAM COAL MONTHLY | 136.55 | 0.00 0.00 | -0.20 -0.15% |
| USD RBD PALM OLEIN | 1,167.50 | 1,167.50 1,167.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 93.94 | 94.73 92.68 | 1.53 1.66% |
| SUGAR #11 WORLD | 18.54 | 0.00 0.00 | 0.04 0.22% |
Chart of the Day
Latest News
Top 5 things to watch in this week
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|