Weekly Market Roundup
MG News | October 17, 2026 at 03:29 PM GMT+05:00

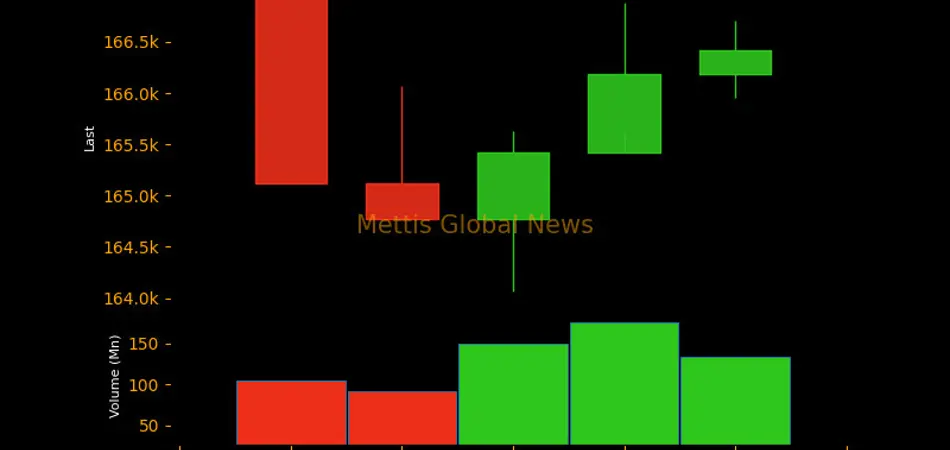
October 17, 2026 (MLN): The benchmark KSE-100 Index closed the week ended October 16, 2026, at 166,419.72 points, losing 669.56 points, or 0.40% week-on-week, from 167,089.28 points recorded on October 9, 2026.
The market remained under pressure during the week as
concerns over potential shipping disruptions in the Strait of Hormuz following
attacks on vessels in the strategic waterway weighed on investor sentiment,
raising uncertainty over regional stability and market conditions._20261017102513315_a0f5a3.jpeg)
Market Capitalization
The Pakistan Stock Exchange's market capitalization declined
to Rs4.680 trillion during the week, compared with Rs4.717tr on October 9,
2026, registering a decrease of approximately Rs36.93bn, or 0.78% week-on-week.
In dollar terms, market capitalization fell from $17.028bn
to $16.901bn, declining by approximately $127.69m, or 0.75% WoW._20261017102526961_d9af12.jpeg)
The market's USD-adjusted return stood at -0.37%, compared
with -0.61% in the previous week, indicating a smaller decline after accounting
for currency movements.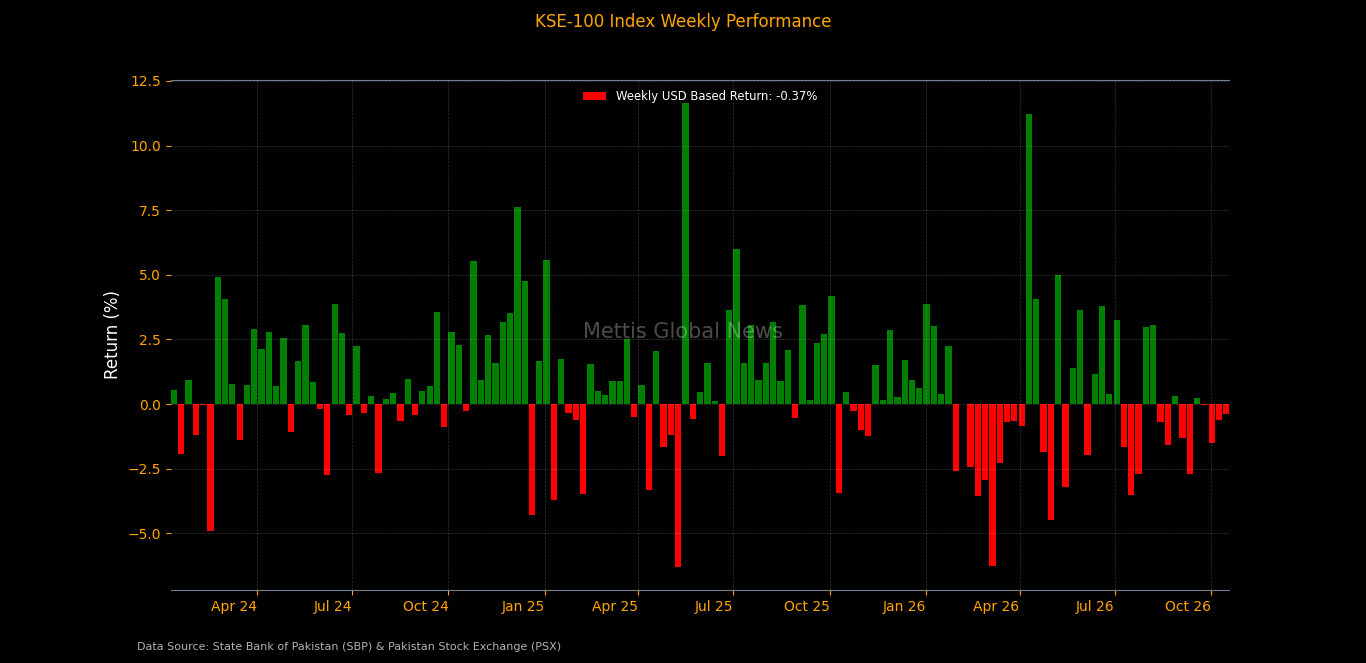
On the macroeconomic front, Pakistan’s
current account deficit widened to $356m in September, taking the
first-quarter FY27 shortfall to $874m, up 15.8% year-on-year, as imports
outpaced exports despite stronger workers’ remittances and secondary income
inflows.
Pakistan’s
large-scale manufacturing output fell 4.96% month-on-month in August 2026,
despite rising 0.67% year-on-year, while cumulative output grew 1.85% in
July-August FY27, driven by automobiles, garments and petroleum products amid
declines in food, chemicals and pharmaceuticals.
The State Bank of Pakistan raised
Rs685.53bn through the latest Treasury Bills auction against bids of Rs2.64tr,
with the 6-month tenor attracting the highest competitive acceptance at
Rs224.20bn as cut-off yields moved in mixed directions across all four tenors.
Pakistan’s
foreign currency deposits rose 0.45% month-on-month to $6.97bn in September
2026, up from $6.94bn in August, but declined 1.27% year-on-year, as higher
resident deposits offset a monthly decline in non-resident holdings.
Pakistan’s
passenger car sales fell 9.8% year-on-year to 10,939 units in September
2026, marking a second consecutive monthly decline with sales down 20.3%
month-on-month, despite a 42.8% increase in cumulative sales to 41,872 units
during 3MFY27.
Index Movers
Sector-wise performance remained broadly negative, with Oil
& Gas Exploration Companies emerging as the largest drag on the KSE-100
Index, shedding 329.78 points, followed by Commercial Banks at 319.41 points,
Cement at 135.70 points, Investment Banks / Investment
Companies / Securities Companies at 109.13 points, and Power Generation &
Distribution at 75.64 points.
Other major negative contributors included Chemical at 27.73
points, Property at 22.54 points, Leather & Tanneries at 18.29 points,
Technology & Communication at 16.33 points, and Automobile Assembler at
13.39 points.
On the upside, Fertilizer provided the largest sectoral
support, adding 170.58 points, followed by Oil & Gas Marketing Companies at
63.18 points, Refinery at 60.13 points, Pharmaceuticals at 40.80 points, and
Food & Personal Care Products at 22.22 points.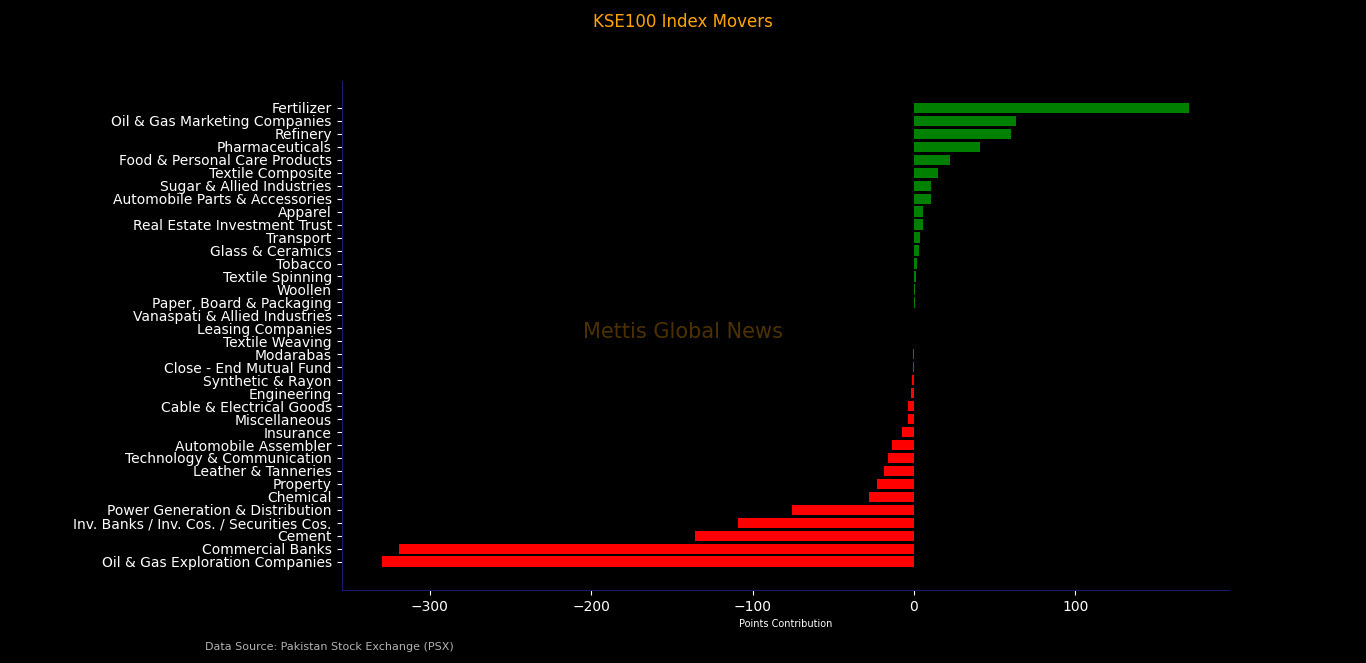
Among individual stocks, FFC emerged as the largest positive
contributor to the index, adding 84.70 points, followed by SYS at 80.73 points,
PSO at 61.60 points, EFERT at 59.83 points, and ATRL at 44.02 points.
On the downside, OGDC was the largest drag on the benchmark,
erasing 160.99 points, followed by UBL at 136.42 points, HBL at 111.35 points,
PTC at 110.50 points, and POL at 94.65 points.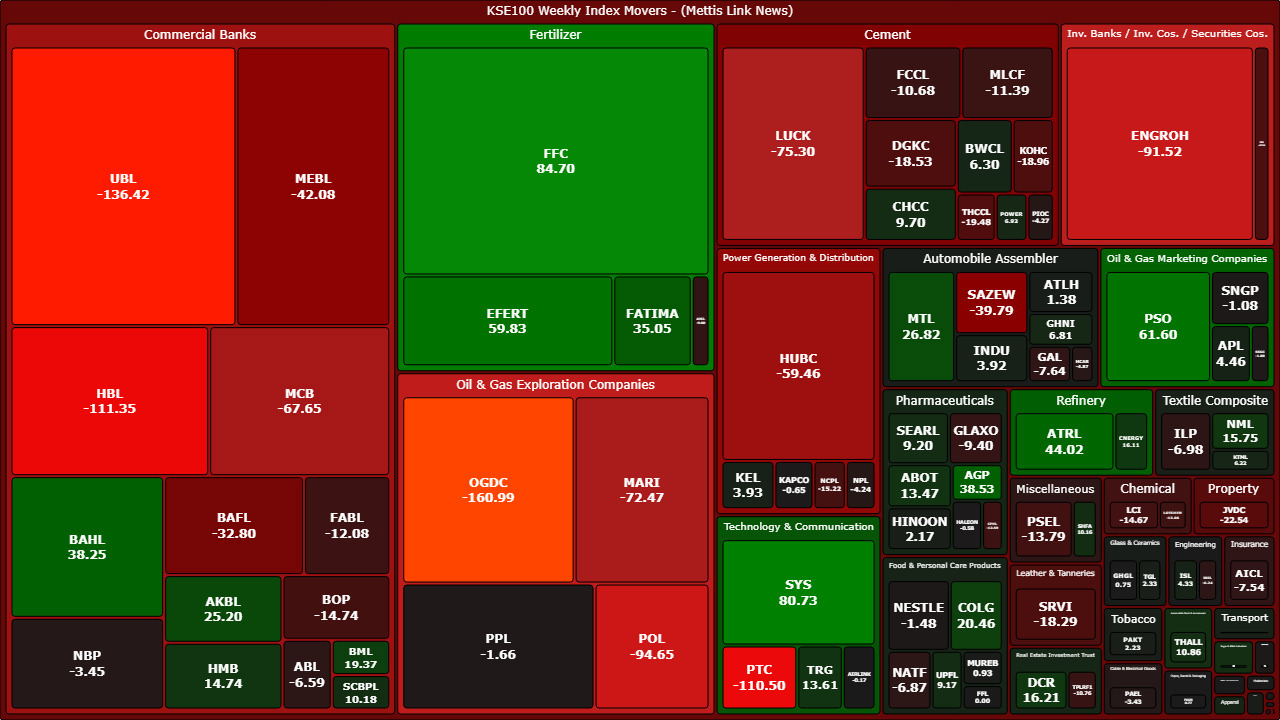
FIPI/LIPI
Foreign investors recorded net equity sales of Rs1.52bn
($5.49m) during the week, primarily driven by net selling of Rs1.68bn ($6.06m)
by Foreign Corporates.
Overseas Pakistanis recorded net equity purchases of
Rs165.17m ($596,287), while Foreign Individuals posted net sales of Rs7.81m
($28,194). Including debt flows, foreign investors recorded net sales of Rs1.52bn
($5.49m).
On the local side, investors recorded net equity purchases
of Rs1.52bn ($5.49m), broadly offsetting foreign equity outflows.
Banks/DFIs were the largest net equity buyers at Rs2.31bn
($8.33m), followed by Companies at Rs1.86bn ($6.72m) and Individuals at
Rs974.47m ($3.52m).
Meanwhile, Mutual Funds recorded the largest net equity
sales at Rs2.96bn ($10.69m), followed by Insurance Companies at Rs460.31m
($1.66m) and Broker Proprietary Trading at Rs205.62m ($742,319).
In the debt market, Banks/DFIs recorded net purchases of
Rs21.55bn ($77.81m), while Mutual Funds recorded net sales of Rs13.05bn ($47.12m)
and Insurance Companies posted net sales of Rs9.06bn ($32.72m). _20261017102543842_fa57cb.jpeg)
Copyright Mettis Link News
Related News
| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 166,419.72 133.15M | 0.14% 233.55 |
| ALLSHR | 100,871.92 395.66M | 0.05% 48.64 |
| KSE30 | 49,316.65 59.50M | 0.05% 23.11 |
| KMI30 | 239,907.60 63.28M | -0.05% -114.34 |
| KMIALLSHR | 65,473.69 245.25M | -0.00% -2.07 |
| BKTi | 45,849.28 9.86M | 0.23% 104.46 |
| OGTi | 33,523.02 3.37M | -0.51% -171.71 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 81,540.00 | 81,795.00 80,850.00 | -60.00 -0.07% |
| BRENT CRUDE | 109.95 | 110.00 104.91 | 4.03 3.80% |
| RICHARDS BAY COAL MONTHLY | 128.50 | 0.00 0.00 | 0.05 0.04% |
| ROTTERDAM COAL MONTHLY | 145.10 | 0.00 0.00 | 0.15 0.10% |
| USD RBD PALM OLEIN | 1,167.50 | 1,167.50 1,167.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 99.04 | 99.34 95.29 | 2.54 2.63% |
| SUGAR #11 WORLD | 20.85 | 21.01 20.47 | -0.28 -1.33% |
Chart of the Day
Latest News
Top 5 things to watch in this week
 Current Account Balance
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|