Inflation projected at 11% in September FY27

MG News | October 01, 2026 at 12:33 AM GMT+05:00

October 01, 2026 (MLN): Inflation is projected to remain
in the range of 10-11% for September 2026, reflecting the pass-through of
elevated global oil prices into domestic energy, transport and food costs, even
as Pakistan's economy consolidates stabilization gains in the early months of
FY2027.
The near-term trajectory remains
encouraging, with activity expected to strengthen as the recovery broadens
across agriculture, manufacturing and private sector credit, according to the
Finance Division's Monthly Economic Update and Outlook for September 2026.
The division flagged elevated oil
prices as the principal risk, through their effect on purchasing power, input
costs and the import bill.
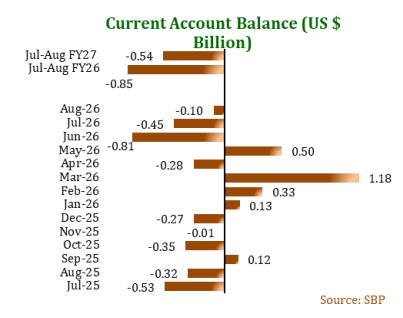
The external account improved, with the current account deficit narrowing to $543mn in Jul-Aug FY2027 from $853mn a year earlier, despite a wider trade gap.
Goods imports rose 11.4% to $11.6bn on
higher oil prices and recovering domestic demand, outpacing a 4% rise in goods
exports to $5.44bn.
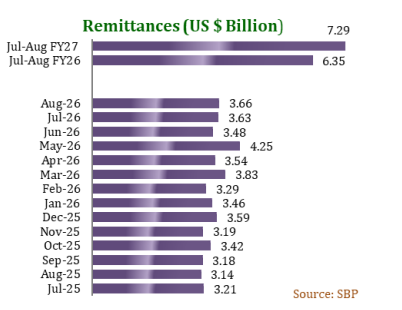
Workers' remittances climbed 14.7% to $7.29bn, more than covering the entire goods and services deficit of $6.75bn, while services exports grew 28.8% to $1.81bn.
Total foreign investment surged 80.2%
to $562.2mn, with FDI up 24% to $494.5mn and portfolio flows turning to a net
inflow of $67.7mn after an outflow a year earlier.
A $3.0bn Eurobond issuance in
September lifted reserves, with SBP's liquid reserves at $21.39bn on September
18, equal to about three months of goods and services imports.
Total liquid reserves stood at
$26.8bn, while the rupee stood at Rs277.1/$ on September 29 against Rs281.4/$ a
year earlier.
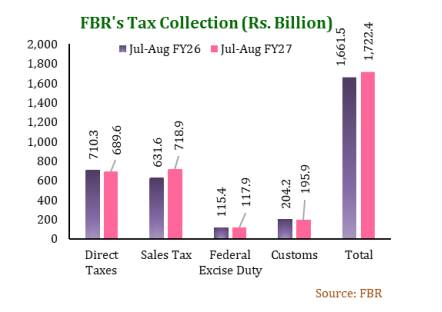
On the fiscal side, FBR net tax collection rose 3.7% to Rs1,722.4bn in Jul-Aug FY2027, led by a 13.8% increase in sales tax to Rs718.9bn. Federal excise rose 2.2% to Rs117.9bn, while direct taxes fell 2.9% to Rs689.6bn and customs dropped 4% to Rs195.9bn.
The consolidated fiscal deficit
widened to Rs596.6bn (0.4% of GDP) in July FY2027 from Rs261.5bn (0.2% of GDP)
a year earlier, as interest payments jumped to Rs792.9bn from Rs490.4bn.
The primary balance stayed in surplus at
Rs196.3bn (0.1% of GDP), against Rs228.9bn (0.2% of GDP) last year.
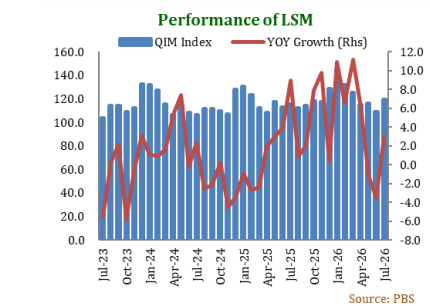
Large-Scale Manufacturing grew 3.03% YoY in July 2026 on top of 8.9% growth a year earlier, and rose 9.5% from June. Automobile output surged 57%, tobacco 35.8% and wearing apparel 22%.
Vehicle production and sales rose 27.6%
and 29.9%, respectively, in Jul-Aug, while cement dispatches edged up 2.8% to
about 8.5mn tonnes. Domestic dispatches gained 8%, offsetting a 16.7% fall in
exports.
Agriculture also started the year on a
positive note, with higher acreage under rice and sugarcane and encouraging
early cotton arrivals. Agricultural credit disbursements grew 16.4% to
Rs271.9bn in July, urea offtake rose 2.9% to 2,755 thousand tonnes during
Kharif 2026 (Apr-Aug), and tractor sales increased 4.7% to 2,294 units in
Jul-Aug. DAP offtake, however, fell 24.5% to 417 thousand tonnes.
Headline CPI inflation rose to 11.1%
YoY in August from 9.2% in July and 3.1% a year earlier, bringing the Jul-Aug
average to 10.2%.
Food, housing and utilities, and
transport together contributed 8.2 percentage points, or about three-quarters
of the headline figure, with food alone accounting for 4.9 percentage points.
Core inflation stood at 8.8% in urban areas and 8.5% in rural areas.
The Monetary Policy Committee held the
policy rate at 11.5% on September 14, citing elevated crude prices as the main
risk to the inflation outlook and saying the stance keeps expectations anchored
and supports the return to the 5-7% medium-term target.
Broad money (M2) contracted 5.3%
between July 1 and September 11, against a 2.8% contraction a year earlier,
driven by seasonal repayment of working capital and commodity financing.
Private sector credit saw a net retirement of Rs364.5bn, though its outstanding
stock remained 13% higher YoY.
To cushion the impact of higher oil
prices, the government introduced the Prime Minister's Fuel Relief Scheme,
which delivers digital assistance to lower-income households without cutting
the petroleum levy.
It also rolled out austerity measures,
including a 50% cut in fuel for official vehicles on non-operational duties, a
ban on new vehicle and durable goods purchases, and curbs on official travel.
The KSE-100 gained 882 points, or
about 0.5%, in August to close at 176,976, lifting market capitalization to
Rs19,830.2bn. The index stood at 169,600 on September 29, up 3.51% from a year
earlier.
Globally, the J.P Morgan Global
Composite PMI rose to 53.5 in August from 52.7. The U.S Federal Reserve raised
its policy rate by 25bps to 3.75-4.00% on September 16, its first increase
since 2023, pointing to a stronger dollar and costlier financing for emerging
markets.
Global oil supply fell 1.6mn barrels
per day to 100.1mn in August, and 2026 supply is projected to drop by 5.7mn
barrels per day, more than twice the expected 2.5mn fall in demand. Inventories
have declined by 507mn barrels since February. The FAO Food Price Index also
rose 1.9% in August to 133.3 points.
Overall, while higher oil prices and
tighter global financial conditions remain key risks, the combination of
resilient remittances, rising services exports, renewed access to international
capital markets, stronger reserves and a broadening manufacturing and
agricultural recovery positions Pakistan to sustain growth while consolidating
macroeconomic stability.
The government said its priorities
include faster revenue mobilization and keeping relief measures temporary and
targeted.
Copyright Mettis Link News
Related News


| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 169,969.33 217.01M | 0.22% 368.92 |
| ALLSHR | 102,892.63 587.53M | 0.20% 206.37 |
| KSE30 | 50,644.26 54.31M | 0.37% 187.28 |
| KMI30 | 243,608.50 54.80M | 0.29% 708.93 |
| KMIALLSHR | 66,655.71 317.82M | 0.13% 87.67 |
| BKTi | 47,135.99 14.01M | 0.54% 251.49 |
| OGTi | 34,716.38 4.43M | -0.08% -29.36 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 83,855.00 | 86,090.00 83,220.00 | -85.00 -0.10% |
| BRENT CRUDE | 98.08 | 99.30 95.12 | 1.92 2.00% |
| RICHARDS BAY COAL MONTHLY | 128.50 | 128.50 128.50 | 5.00 4.05% |
| ROTTERDAM COAL MONTHLY | 142.95 | 142.95 137.95 | 5.65 4.12% |
| USD RBD PALM OLEIN | 1,167.50 | 1,167.50 1,167.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 90.49 | 91.96 88.58 | 1.11 1.24% |
| SUGAR #11 WORLD | 18.62 | 19.12 18.53 | -0.22 -1.17% |
Chart of the Day
Latest News
Top 5 things to watch in this week
 SBP Interventions in Interbank FX Market
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|