
Weekly Market Roundup
MG News | November 21, 2026 at 01:03 PM GMT+05:00

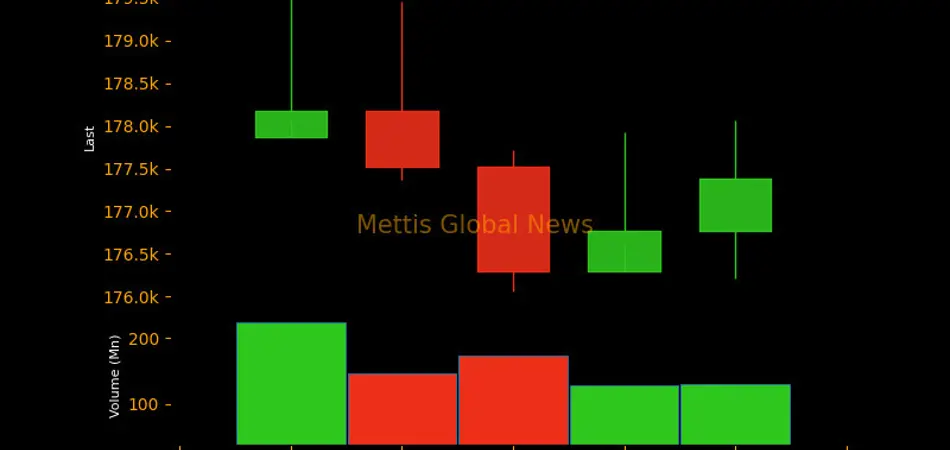
November 21, 2026 (MLN): The KSE-100 Index closed the
week ended November 20, 2026, at 177,382.57 points, declining 491.31
points, or 0.28% week-on-week (WoW), from 177,873.88 points recorded on
November 13, 2026.
The benchmark faced selling pressure amid cautious investor
sentiment over political uncertainty and geopolitical tensions, with losses in
major index-heavy sectors, particularly banking, cement, and oil & gas
exploration, outweighing gains in fertilizer, power, and investment companies._20261121070159643_620ae2.jpeg)
Market Capitalization
The Pakistan Stock Exchange's market capitalization declined
to Rs4.921 trillion during the week, compared with Rs4.936 trillion on November
13, 2026, registering a decrease of approximately Rs14.49bn, or 0.29% WoW.
In dollar terms, market capitalization fell from $17.844bn
to $17.797bn, declining by approximately $46.55m, or 0.26% WoW._20261121070219472_87e739.jpeg)
The KSE-100 Index recorded a weekly decline of 0.28% in
rupee terms, while dollar-denominated market capitalization decreased by 0.26%.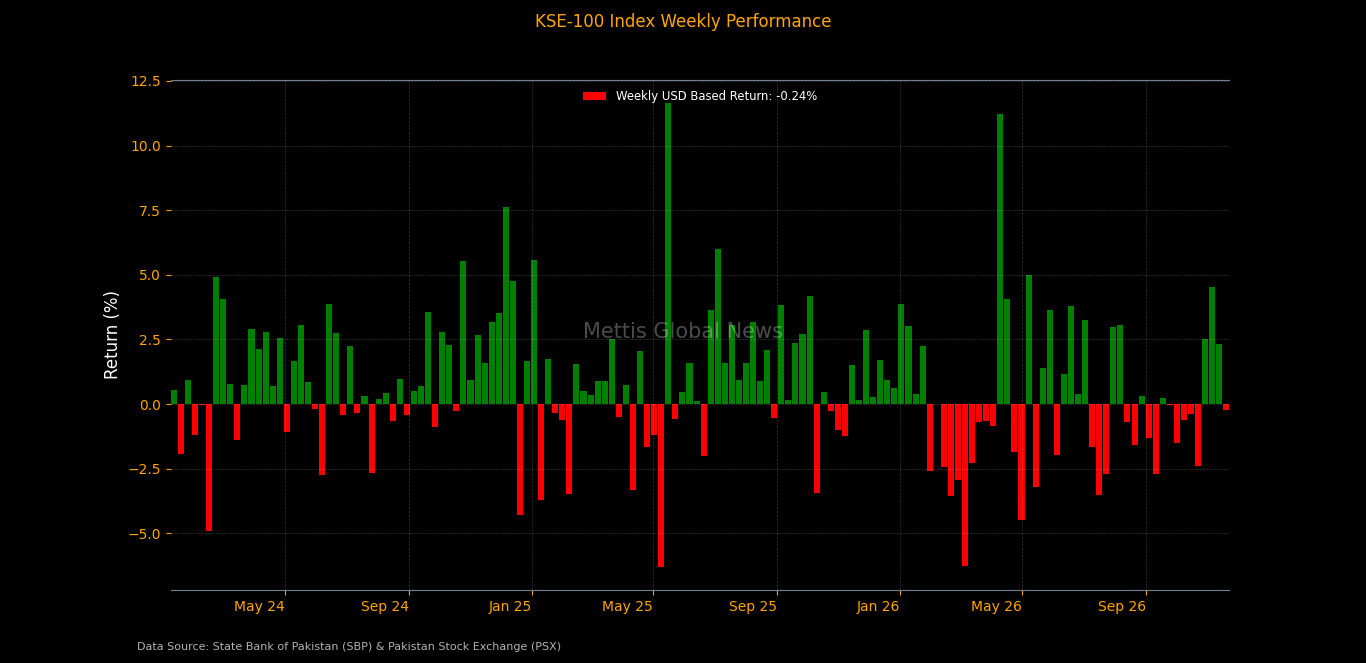
On the macroeconomic front, Pakistan’s
Large-Scale Manufacturing (LSM) output grew 2.45% YoY and 3.18% MoM in
September 2026, while cumulative growth reached 2.07% in 1QFY27,
driven by automobiles, garments and petroleum products, amid continued weakness
in food, chemicals, pharmaceuticals and iron & steel.
Pakistan’s
REER increased 1.59% MoM and 6.40% YoY to 110.62 in October 2026,
while NEER rose 0.83% MoM and 1.02% YoY to 38.38, reflecting the rupee’s
relative strengthening against trading partners, with the higher REER
indicating reduced export competitiveness.
Pakistan’s
net FDI inflows rose 31.7% YoY to $216 million in October 2026,
while cumulative FDI during 4MFY27 increased 22.4% to $935.7m, lifting total
foreign investment to $349.3m in October amid net FPI outflows.
Pakistan’s
current account posted a surplus of $39m in October 2026, reversing
September’s $371m deficit, supported by a narrower goods trade gap and higher
remittances, while the financial account recorded net inflows of $204m.
Consumer
financing in Pakistan rose 41.75% YoY to Rs1.39tr in October 2026,
driven by strong growth in auto, housing and personal loans, while private
sector credit increased 17.46% YoY to Rs11.4tr, led by manufacturing and
agriculture-sector borrowing.
Index Movers
Sector-wise performance remained predominantly negative,
with Commercial Banks emerging as the largest drag on the KSE-100 Index,
erasing 333.92 points, followed by Cement at 281.02 points, Oil & Gas
Exploration Companies at 214.21 points, Technology & Communication at
203.23 points, and Automobile Assembler at 175.23 points.
Other major negative contributors included Miscellaneous at
133.14 points, Oil & Gas Marketing Companies at 81.62 points, Insurance at
73.19 points, Refinery at 54.15 points, and Food & Personal Care Products
at 26.43 points.
On the upside, Investment Banks / Investment Companies /
Securities Companies emerged as the largest contributor to the benchmark,
adding 662.44 points, followed by Fertilizer at 239.22 points, Power Generation
& Distribution at 174.83 points, Engineering at 23.29 points, and Leather
& Tanneries at 18.44 points.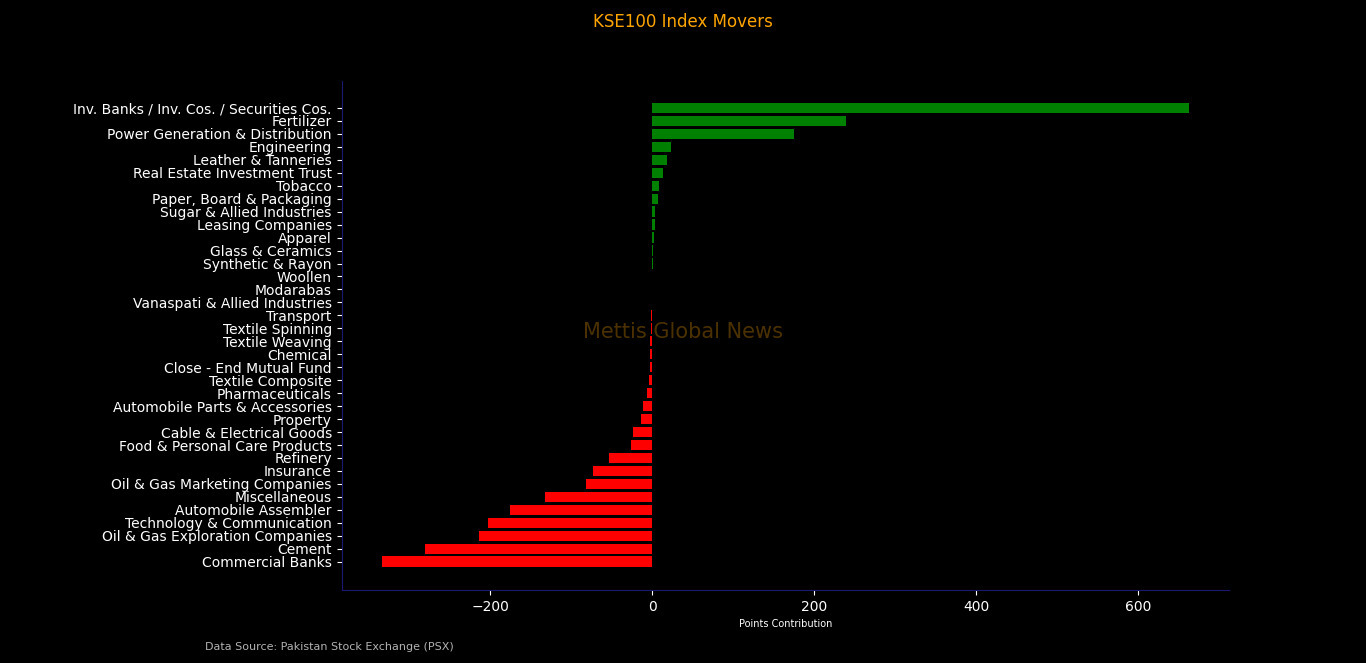
Among individual stocks, ENGROH emerged as the largest
positive contributor to the index, adding 642.33 points, followed by EFERT at
266.38 points, HUBC at 196.71 points, BAHL at 74.20 points, and FFC at 62.19
points.
Other notable positive contributors included NBP at 49.84
points, MLCF at 31.94 points, HMB at 25.32 points, PSX at 20.11 points, and
SRVI at 18.44 points.
On the downside, LUCK was the largest drag on the benchmark,
erasing 222.38 points, followed by MEBL at 141.81 points, SYS at 139.16 points,
PSEL at 134.02 points, and HBL at 126.03 points._20261121070254376_3c4b8a.jpeg)
FPI/LIPI
Foreign investors recorded net equity sales of approximately
$232,390 during the week, mainly driven by net selling of $298,348 by Overseas
Pakistanis, while Foreign Corporates recorded net purchases of $62,840. Foreign
Individuals posted net purchases of $3,118.
Local investors recorded net equity purchases of
approximately $231,638.
Individuals led the buying with net purchases of $7.92m,
followed by Companies at $3.96m, Banks/DFIs at $1.78m, Insurance Companies at
$44,941, while NBFCs recorded net sales of $180,971.
Broker Proprietary Trading led the selling with net sales of
$8.28m, followed by Mutual Funds at $4.23m and Other Organizations at $786,874.
In the debt market, Mutual Funds recorded net purchases of
$113.81m, followed by Insurance Companies at $7.31m, Other Organizations at
$3.20m, and Individuals at $64,691.
Banks/DFIs were the largest net sellers at $124.08m,
followed by Companies at $304,373 and Broker Proprietary Trading at $3,704._20261121070243233_b31c5d.jpeg)
Copyright Mettis Link News
Related News

| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 177,382.57 129.46M | 0.35% 610.38 |
| ALLSHR | 106,289.83 618.70M | 0.13% 141.72 |
| KSE30 | 51,822.39 81.72M | 0.48% 245.89 |
| KMI30 | 255,823.27 110.29M | 0.65% 1649.18 |
| KMIALLSHR | 68,759.73 247.31M | 0.07% 47.95 |
| BKTi | 48,432.52 12.51M | 0.23% 109.40 |
| OGTi | 35,759.50 5.47M | -0.13% -46.88 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 58,415.00 | 62,530.00 57,990.00 | -3625.00 -5.84% |
| BRENT CRUDE | 92.19 | 92.89 90.06 | 0.21 0.23% |
| RICHARDS BAY COAL MONTHLY | 127.15 | 0.00 0.00 | 3.60 2.91% |
| ROTTERDAM COAL MONTHLY | 131.75 | 0.00 0.00 | -0.50 -0.38% |
| USD RBD PALM OLEIN | 1,182.50 | 1,182.50 1,182.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 83.17 | 83.25 80.78 | 0.73 0.89% |
| SUGAR #11 WORLD | 17.07 | 17.31 16.82 | -0.09 -0.52% |
Chart of the Day
Latest News
Top 5 things to watch in this week
 Large Scale Manufacturing (LSMI)
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|