Weekly Market Roundup
MG News | November 14, 2026 at 12:04 PM GMT+05:00

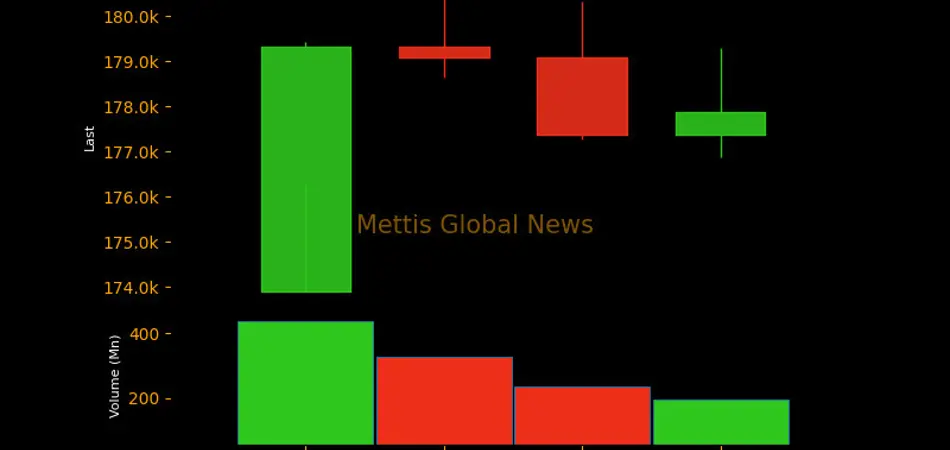
November 14, 2026 (MLN): The benchmark KSE-100 Index
closed the week ended November 13, 2026, at 177,873.88 points, gaining 3,987.19
points, or 2.29% week-on-week (WoW), from 173,886.69 points recorded on
November 06, 2026.
The benchmark maintained its upward momentum during the week, crossing the 177,000-point level.
The market initially faced pressure amid concerns over
rising international oil prices but recovered from early losses as buying
interest emerged in oil and gas stocks. Mari Energies led the recovery
following its subsidiary's copper
and gold discovery at the East Siah Diq-1 target in Chagai, Balochistan,
providing support to the benchmark.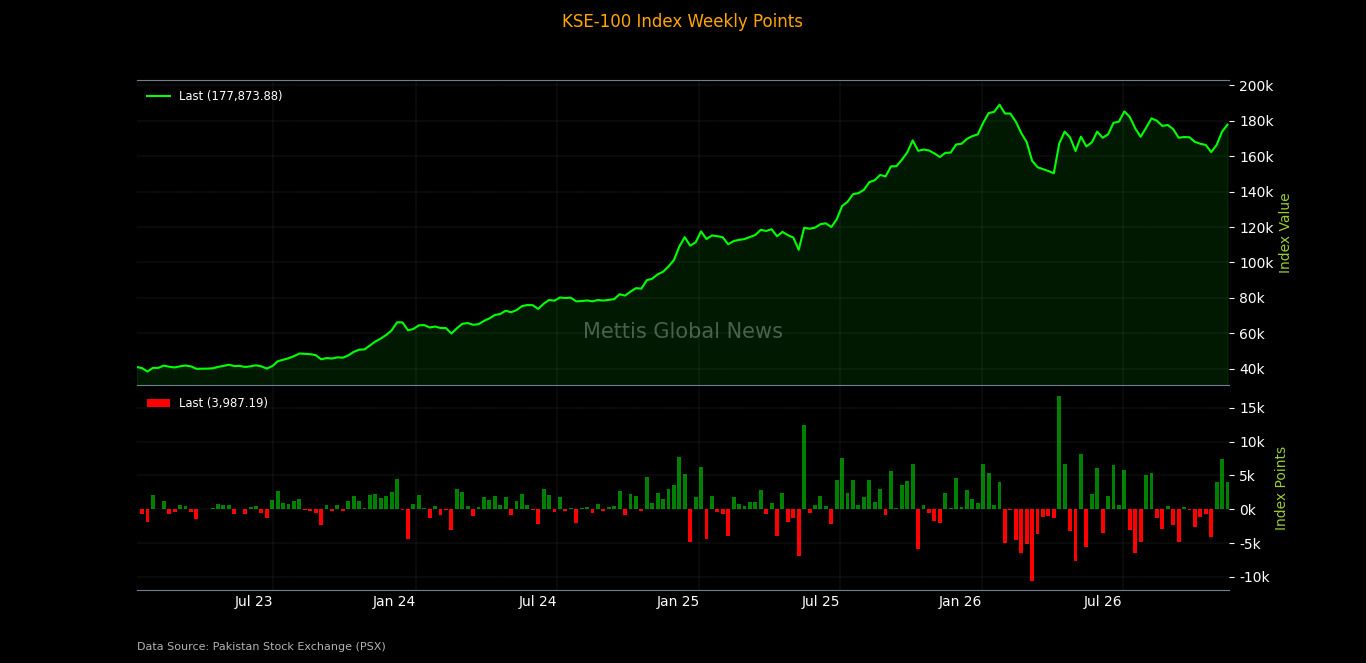
Market Capitalization
The Pakistan Stock Exchange's market capitalization
increased to Rs4.936 trillion during the week, compared with Rs4.830tr on
November 06, 2026, registering an increase of approximately Rs105.44bn, or
2.18% WoW.
In dollar terms, market capitalization rose from $17.459bn
to $17.844bn, increasing by approximately $384.81m, or 2.20% WoW.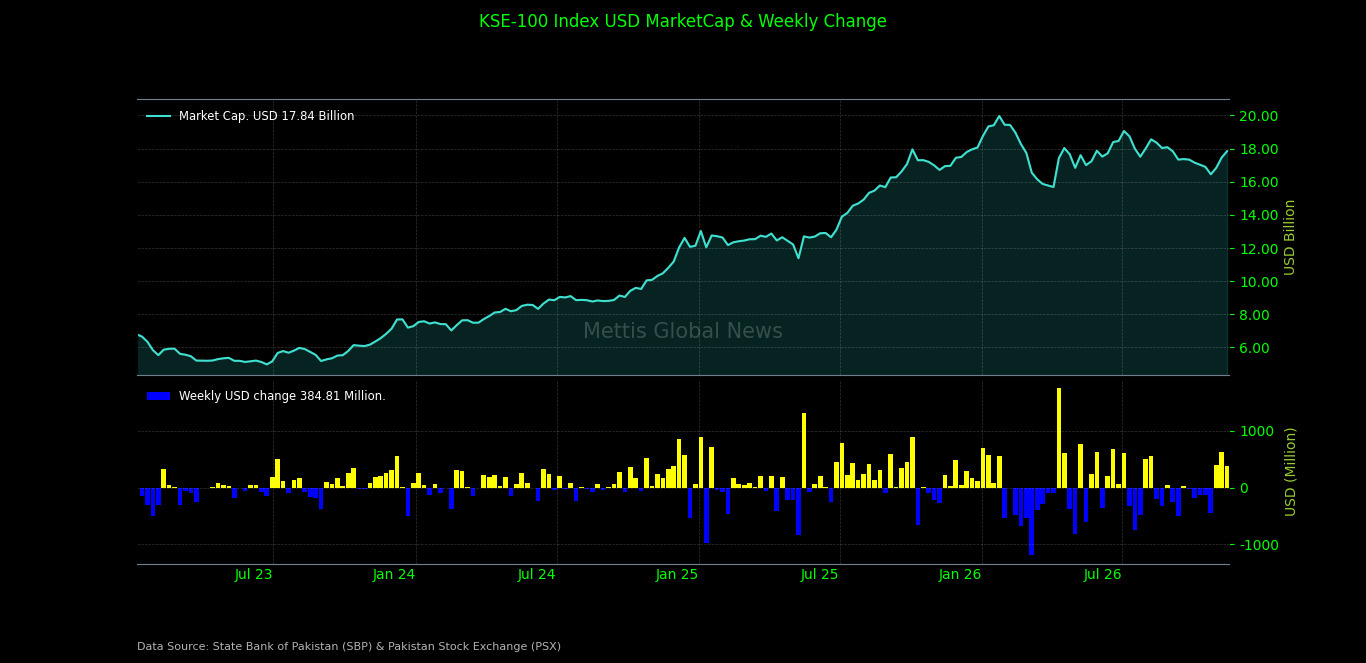
The KSE-100 Index recorded a weekly gain of 2.29% in rupee
terms, while dollar-denominated market capitalization increased by 2.20%._20261114065911291_5b0de5.jpeg)
On the macroeconomic front, Pakistan’s
passenger car sales surged 60.1% YoY and 97.8% MoM to 21,635 units in
October 2026, while cumulative sales for 4MFY27 rose 48.3% to 63,507 units, led
by strong demand for Suzuki Alto and Swift.
Pakistan’s
total debt and liabilities increased 6.5% YoY to Rs98.88tr by September
2026, while debt servicing surged 33% YoY to Rs2.90tr during 1QFY27, driven by
higher principal repayments and interest payments.
Pakistan’s
central government debt increased 7.9% YoY to Rs82.66 trillion in September
2026, despite declining 0.3% MoM, with domestic debt accounting for the largest
share at Rs57.76tr.
Pakistan’s
net mobilization through National Savings Schemes (NSS) rose 12% YoY to
Rs32.87bn in September 2026, while cumulative inflows for 1QFY27 increased 16%
to Rs118.92bn, led by the Others category and Regular Income Certificates.
Pakistan’s
workers’ remittances increased 13.8% YoY and 8.5% MoM to $3.89bn in October
2026, taking cumulative inflows to $14.76bn during July–October FY27, with
Saudi Arabia remaining the largest source of remittances.
Index Movers
Sector-wise performance remained predominantly positive,
with Oil & Gas Exploration Companies emerging as the largest contributor to
the KSE-100 Index, adding 1,058.39 points, followed by Commercial Banks at
1,036.30 points, Cement at 545.09 points, Fertilizer at 316.98 points, and
Investment Banks / Investment Companies / Securities Companies at 187.35
points.
Other major positive contributors included Automobile
Assembler at 184.33 points, Oil & Gas Marketing Companies at 162.11 points,
Miscellaneous at 144.41 points, Power Generation & Distribution at 119.54
points, and Food & Personal Care Products at 78.75 points.
On the downside, Refinery was the largest drag on the
benchmark, erasing 46.36 points, followed by Technology & Communication at
31.80 points, Insurance at 26.94 points, Property at 3.09 points, and Apparel
at 1.13 points.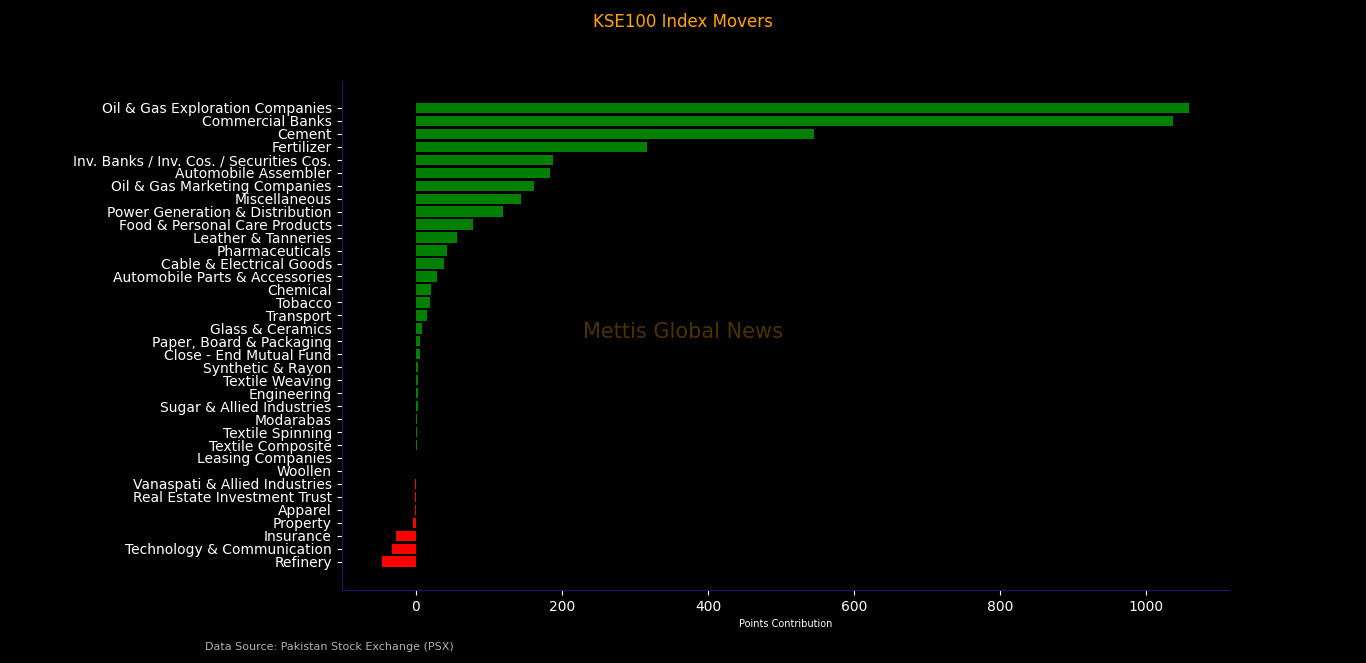
Among individual stocks, MARI emerged as the largest
positive contributor to the index, adding 582.52 points, followed by UBL at
264.44 points, LUCK at 250.26 points, PPL at 243.87 points, and HBL at 201.63
points.
Other notable positive contributors included OGDC at 185.45
points, FFC at 185.26 points, ENGROH at 163.96 points, BAHL at 155.83 points,
and MCB at 144.02 points.
On the downside, NBP was the largest drag on the benchmark,
erasing 47.87 points, followed by ATRL at 28.06 points, AICL at 26.94 points,
PTC at 21.39 points, and CNERGY at 18.30 points._20261114065945258_35f9f0.jpeg)
FPI/LIPI
Foreign investors recorded net equity purchases of
approximately $3.62m during the week, mainly driven by net buying of $7.39m by
Foreign Corporates.
Overseas Pakistanis recorded net sales of $3.71m, while
Foreign Individuals posted net sales of $54,721. In the debt market, Overseas
Pakistanis recorded net purchases of $12,912.
Local investors recorded net equity sales of approximately
$3.62m.
Mutual Funds led the buying with net purchases of $25.81m,
followed by Other Organizations at $5.14m and Companies at $1.47m.
Individuals were the largest net sellers at $21.21m,
followed by Banks/DFIs at $10.31m, Insurance Companies at $2.91m, Broker
Proprietary Trading at $1.28m, and NBFCs at $329,593.
In the debt market, Banks/DFIs recorded net purchases of
$89.44m, followed by Insurance Companies at $12.19m, Other Organizations at
$6.43m, Companies at $509,468, and Individuals at $106,718.
Mutual Funds recorded net sales of $108.12m, followed by
Broker Proprietary Trading at $569,133.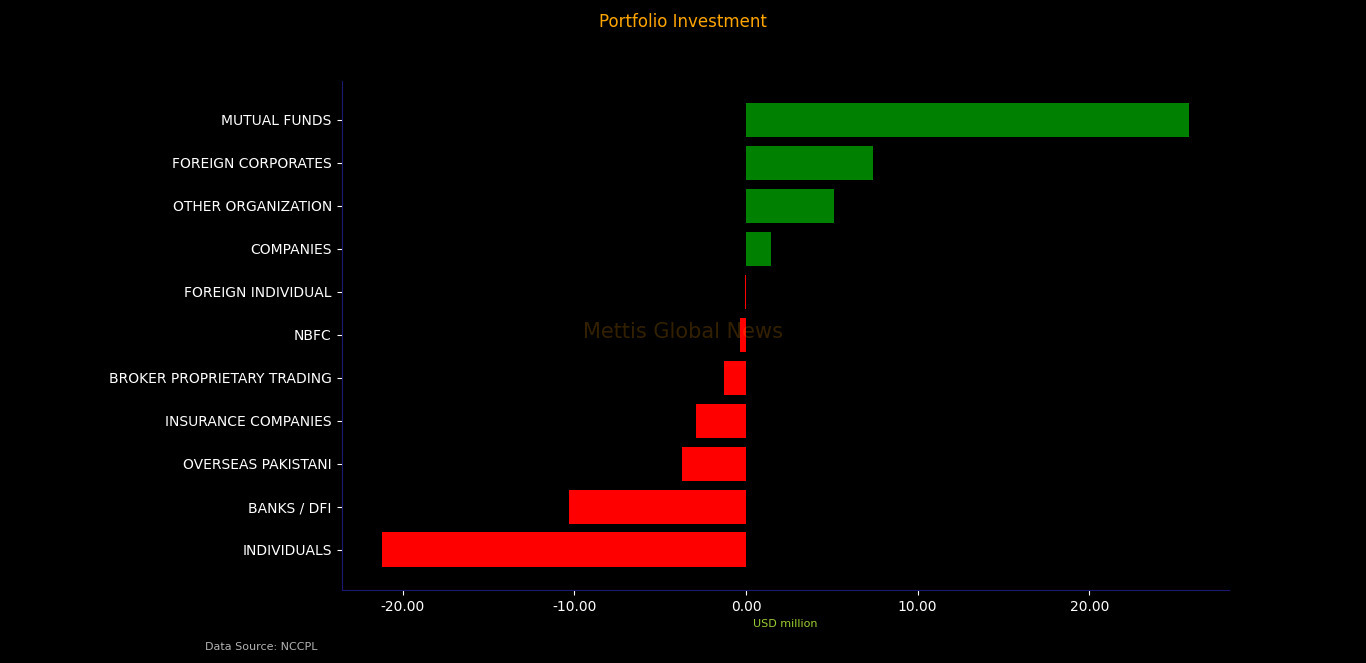
Copyright Mettis Link News
Related News

| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 177,873.88 195.45M | 0.28% 500.11 |
| ALLSHR | 106,712.07 1,040.19M | 0.56% 589.19 |
| KSE30 | 51,887.21 103.81M | 0.29% 152.18 |
| KMI30 | 255,042.46 89.67M | 0.46% 1169.47 |
| KMIALLSHR | 69,162.85 342.71M | 0.85% 584.42 |
| BKTi | 48,733.27 19.48M | -0.22% -108.13 |
| OGTi | 36,043.06 20.06M | 2.70% 947.37 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 67,255.00 | 68,420.00 66,500.00 | -1660.00 -2.41% |
| BRENT CRUDE | 96.29 | 97.13 95.06 | 0.47 0.49% |
| RICHARDS BAY COAL MONTHLY | 127.15 | 0.00 0.00 | -1.45 -1.13% |
| ROTTERDAM COAL MONTHLY | 138.00 | 138.00 137.90 | 0.60 0.44% |
| USD RBD PALM OLEIN | 1,182.50 | 1,182.50 1,182.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 88.92 | 89.64 87.80 | 0.18 0.20% |
| SUGAR #11 WORLD | 18.40 | 18.54 18.16 | 0.18 0.99% |
Chart of the Day
Latest News
Top 5 things to watch in this week
 Auto Numbers
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|