MPC Preview: Oil bites. Will SBP bite back?
MG News | October 26, 2026 at 12:19 PM GMT+05:00

October 26, 2026 (MLN): When the Monetary Policy Committee (MPC) last met on September 14, three of its ten members wanted to raise rates by a full percentage point. The majority chose to wait, warning that hostilities in the Middle East were pushing oil prices higher. Six weeks later, crude is trading above $114 a barrel, and the market is betting that the wait is over.
Nearly six in ten participants in a Mettis Global survey, 58.7%, expect the State Bank of Pakistan (SBP) to raise its policy rate from 11.5% when it announces its decision later today. Most of them expect a measured step: 44.4% see a 50 basis point increase to 12%, 12.7% expect 100bps and 1.6% expect a larger move. The remaining 41.3% think the SBP will hold, and none expect a cut. The median response, gathered between October 21 and 24, is a 50bps hike.
The SBP’s choice is harder than the survey suggests. Electricity and fuel costs are pushing prices up, and inflation expectations rose in September. Against that, core inflation is easing, the rupee is steady, and industry is still struggling to recover.
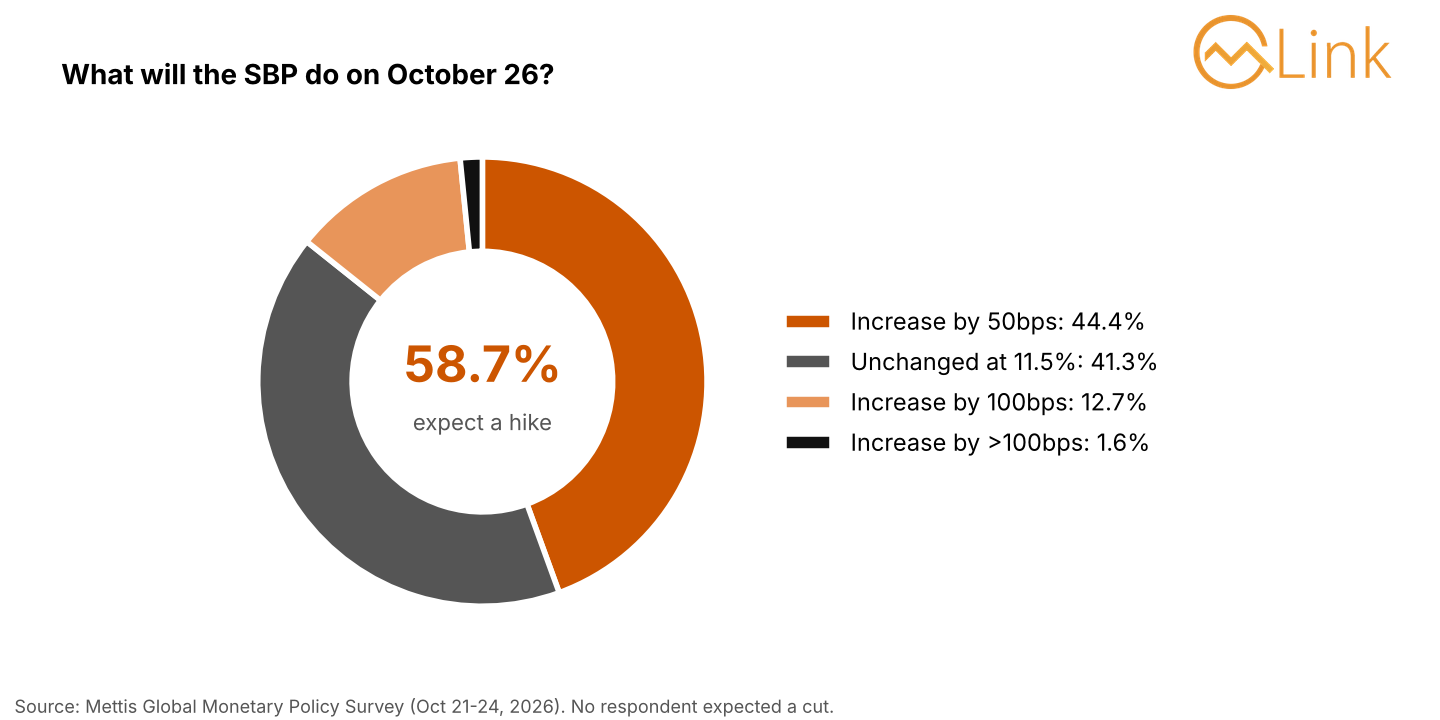
|
Expected
decision, Oct 26 MPC |
Share |
|
Increase by
50bps (to 12.0%) |
44.4% |
|
Increase by
100bps (to 12.5%) |
12.7% |
|
Increase by
more than 100bps |
1.6% |
|
All hike
expectations |
58.7% |
|
Unchanged at
11.5% |
41.3% |
|
Total |
100.0% |
Source: Mettis Global Monetary Policy Survey, October 21-24, 2026.
Energy and
geopolitics dominate respondents’ concerns. 47.6% named rising global
oil prices as the biggest threat to the macroeconomic outlook over the next six
months, and 38.1% named geopolitical tensions. Together, that is 85.7% of
the sample. The two camps put the emphasis differently, as one part expected
a hike and pointed to oil, while the other half of the hold camp pointed to
geopolitical tensions more broadly.
Inflation is the main lens. Thirty-four of 56.7% said inflationary pressure is what drives their view of the SBP’s next moves, and 63.5% listed core inflation among the factors behind the central bank’s current stance. 55.0% expect average FY27 CPI inflation above 9%, well above the SBP’s 5-7% target range.
Respondents are less worried about the
currency as they expect the rupee to stay broadly stable over six months, while average optimism about growth for the rest of
FY27 was 5.2 out of 10.
Inflation:
Headline CPI
inflation slowed to 10.3% year-on-year in September from 11.1% in August,
according to the Pakistan Bureau of Statistics. The drop owes much to the base.
Prices rose 1.3% month-on-month, against 2.1% in September 2025. Monthly
increases of 1.2%, 1.2% and 1.3% in July, August and September add up to a rise
of about 3.7% in one quarter. Inflation averaged 10.2% in July-September,
against 4.3% a year earlier.
Energy did most of the work in September. Electricity charges rose 15.3% month-on-month and motor fuel 10.8%. Housing and utilities together with transport accounted for 1.07 percentage points of the 1.27% monthly rise. Food prices rose only 0.2%. Wholesale inflation picked up to 13.3% from 11.8%, which points to further cost pressure in the pipeline.
Yields:
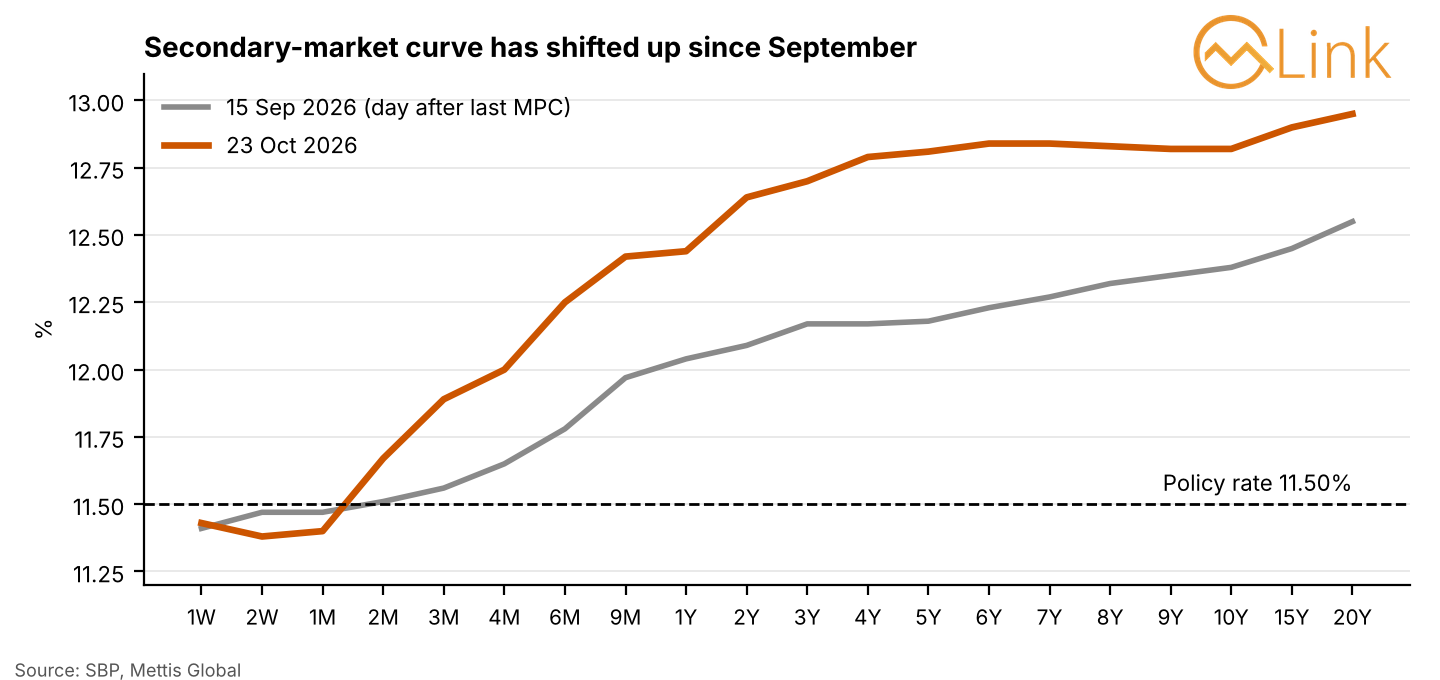
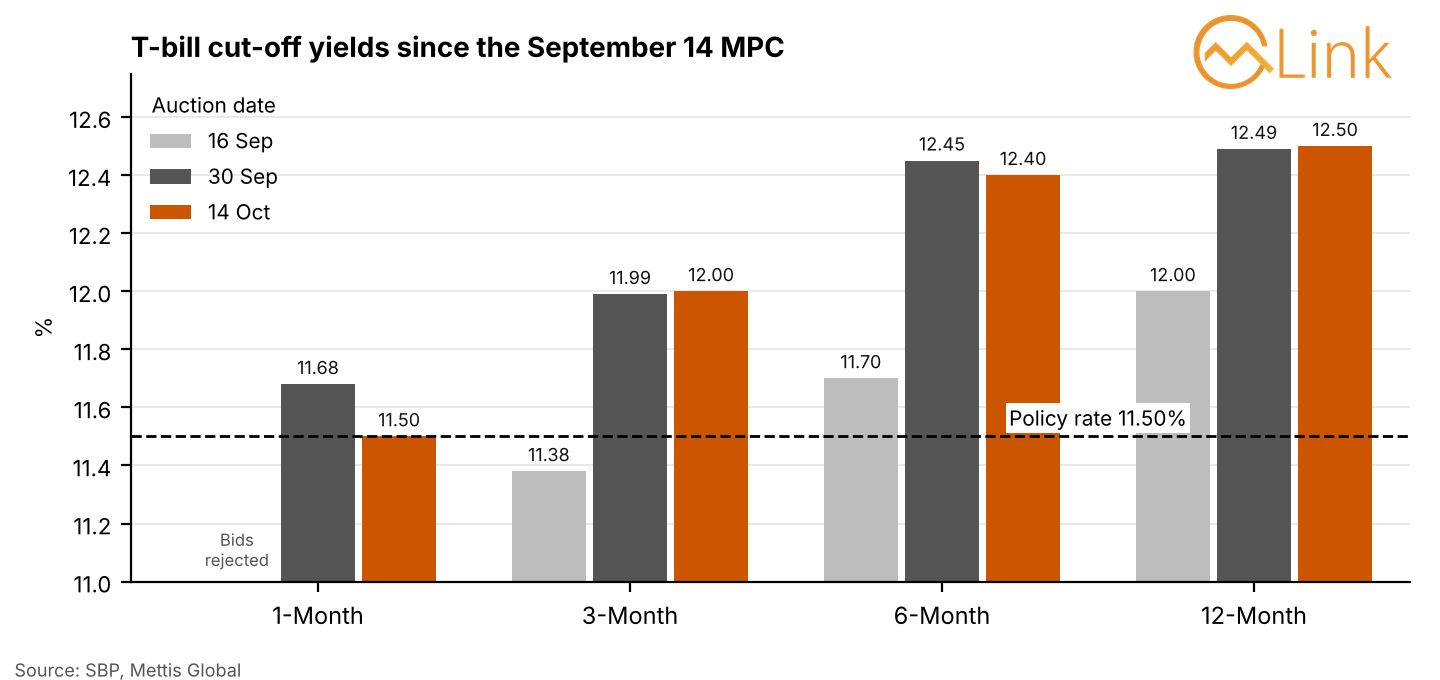
Primary auctions tell the same story. At the October 14 T-bill auction, cut-off yields were 11.50% for 1 month, 12.00% for 3 months, 12.40% for 6 months and 12.50% for 12 months. That is 62bps, 70bps and 50bps above the 3-, 6- and 12-month cut-offs at the first auction after the September meeting, held on September 16.
The government raised Rs685.5 billion against a Rs550bn target on bids of
Rs2.64 trillion. In the 12-month paper, though, it accepted only Rs10.5bn of
Rs416bn in competitive bids, which suggests it was unwilling to lock in funding
at the rates investors were asking.
A 3-month cut-off of 12% is roughly where that paper would trade if a 50bps hike were already expected. Yields are not a forecast of the SBP’s decision, however. After the April hike, the 12-month cut-off climbed to 12.99% on June 10. The SBP held, and by July 8 the cut-off had fallen back to 11.49%.
Three of the ten MPC members already voted for a 100bps increase in September. The main risk the majority flagged then, Middle East hostilities pushing up oil prices, has since grown. The SBP’s September compendium recorded an August average of $84.4 per barrel for the World Bank’s three-benchmark crude price and $97.3 for Saudi Arabian Light. A price above $114 is about 35% and 17% higher than those averages, respectively.
Higher oil would widen the import bill, which was already up 13.4% year-on-year in July. It would also push domestic fuel and transport costs higher, at a time when consumer and business inflation expectations are rising, wholesale inflation is accelerating and trimmed-mean core is moving up. The policy rate is only 1.2 ppt above headline inflation. Private-sector credit grew 13.4% in late August, suggesting demand has not been choked. The yield curve has also moved, so tightening now would follow the market rather than shock it.
In Mettis Global’s analysis, the evidence leans slightly towards a 50bps increase to 12%, but a hold remains a strong possibility. The committee was already split 7-3 in September; the majority-cited oil risk has intensified, inflation expectations have risen, and the curve has repriced. Only two members would need to change their vote for a majority to back a hike.
A 50bps move would show the
SBP is taking the oil shock seriously without adding much pressure on a weak
industrial recovery.
The main risk to this view is that the SBP treats the oil spike as a supply shock, points to softer core momentum and a favourable October base, and holds with hawkish guidance tied to oil. A larger move is also possible if the MPC expects further disruption to Gulf energy supplies or shipping; 100bps, the size the September dissenters favoured, would come into play.
Related News
| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 161,976.67 60.33M | -0.25% -398.21 |
| ALLSHR | 98,337.88 189.98M | -0.29% -282.24 |
| KSE30 | 47,708.34 20.40M | -0.24% -114.82 |
| KMI30 | 231,713.00 18.81M | -0.44% -1021.00 |
| KMIALLSHR | 63,677.49 96.17M | -0.44% -278.19 |
| BKTi | 44,641.89 6.98M | -0.18% -82.28 |
| OGTi | 32,873.98 0.89M | -0.48% -159.74 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 79,910.00 | 81,450.00 79,240.00 | -1295.00 -1.59% |
| BRENT CRUDE | 115.22 | 115.97 114.00 | -1.50 -1.29% |
| RICHARDS BAY COAL MONTHLY | 128.50 | 0.00 0.00 | -0.35 -0.27% |
| ROTTERDAM COAL MONTHLY | 147.10 | 0.00 0.00 | 0.10 0.07% |
| USD RBD PALM OLEIN | 1,182.50 | 1,182.50 1,182.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 101.50 | 102.63 100.69 | -1.77 -1.71% |
| SUGAR #11 WORLD | 20.26 | 0.00 0.00 | 0.02 0.10% |
Chart of the Day
Latest News
Top 5 things to watch in this week
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|