SE Fruits IPO Goes Silent: Money Stuck, Calls Unanswered
MG News | October 13, 2026 at 10:55 AM GMT+05:00

October 13, 2026 (MLN): Fourteen days after the
public subscription closed for SE Fruits and Vegetable Limited’s (SEFL) PKR 1.2
billion IPO, investors who want to know what has happened to their money are
getting no answers.
A few retail applicants told Mettis Global they have heard nothing since applying, and that attempts to reach the lead manager directly went unanswered.
The investors’ money is still blocked. There has been no
allotment, no refund and no explanation. The prospectus does answer one
question, though, who pays if the delay continues. The answer is not the
investors.
The penalty goes to PSX
Section 13.8 of the prospectus (p.182) requires shares to be
allotted, issued and credited within five working days of the close of
subscription, which was October 6. If the company misses that deadline, it
shall pay nominal, non-substantial penalty to PSX. Investors receive none of
it.
Investors are compensated only in narrow cases. Under
Section 68(2) of the Companies Act, cited in Section 13.6 of the prospectus,
directors owe a 2% monthly surcharge if a required refund is paid late. They
are excused if they prove the delay “was not on their own account and was not
due to any misconduct or negligence on their part.”
Separately, if PSX does not grant permission to list within
21 days of subscription closing, all money must be refunded “forthwith”
(pp.12–13). That deadline is October 20. PSX can extend it to 42 days, until
November 10, but only by giving notice within the first 21 days. Until one of
these triggers is reached, nothing in the prospectus compensates investors for
the wait.
Compare that with what the intermediaries earn. The
prospectus budgets an advisory fee of 1.99% for the lead managers, about PKR
23.9 million at the floor price, plus 1% underwriting commission on the retail
tranche (pp.158–159).
Who prepared the prospectus, and what they promised
The prospectus is the company’s document, signed by its
directors. Under the Public Offering Regulations, it is prepared and filed
through the Consultant to the Issue. For SEFL, those were Topline Securities
and Growth Securities.
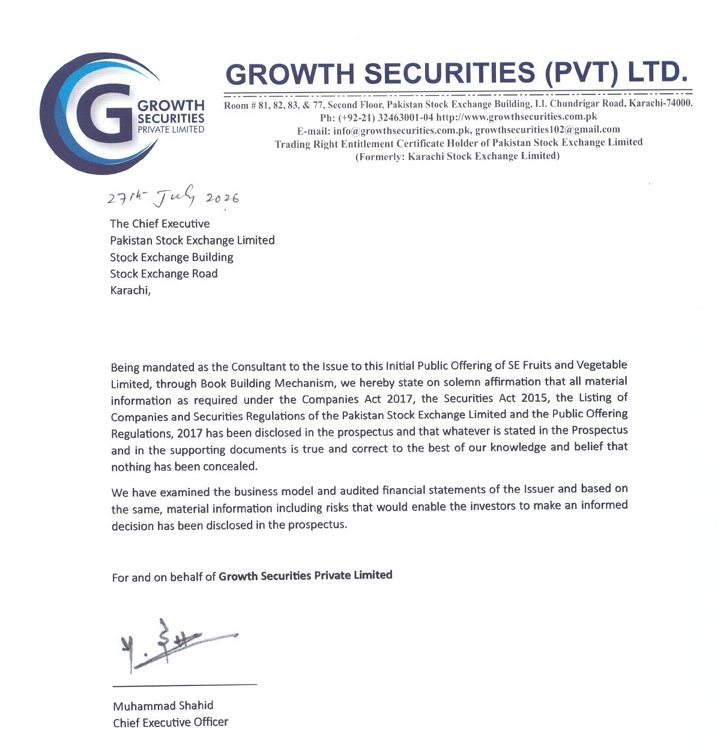
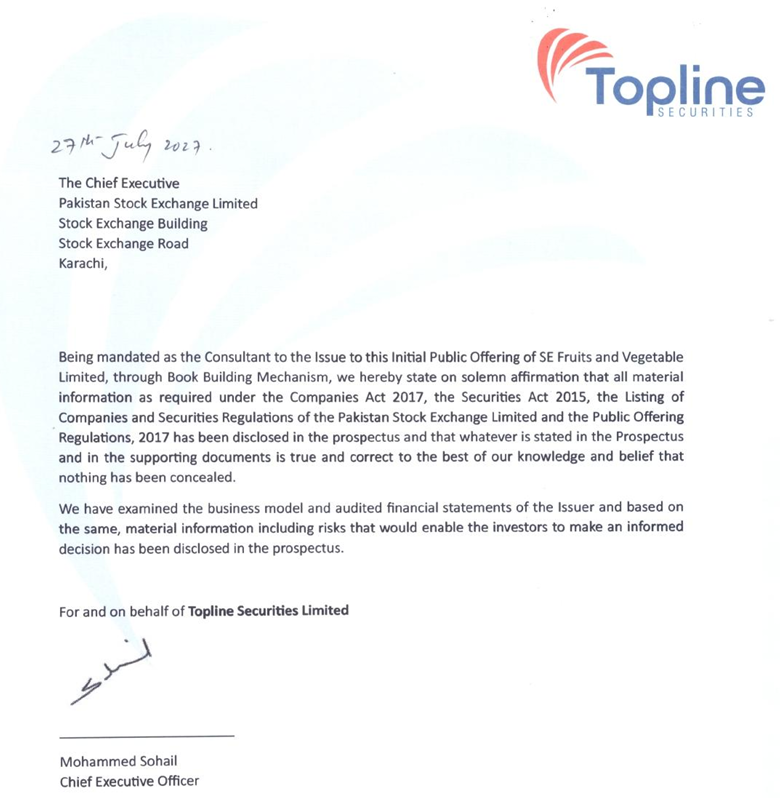
Both firms signed an identical undertaking to PSX’s chief
executive (pp.101–102):
“We hereby state on solemn affirmation that all material
information … has been disclosed in the prospectus and that whatever is stated
in the Prospectus and in the supporting documents is true and correct to the
best of our knowledge and belief that nothing has been concealed.
We have examined the business model and audited financial
statements of the Issuer and based on the same, material information including
risks that would enable the investors to make an informed decision has been
disclosed in the prospectus.”
The Investment Brief that Topline circulated to investors
takes a different tone. Its disclaimer states that the information “has been
obtained from the Company” and “reviewed and agreed upon by the Company,” that
“no representation or warranty is made by Topline Securities Limited,” and that
Topline “disclaims any and all liability based on such information or omissions
thereof.”
The same brief sold the deal hard. It called FY26 “a record
year, achieved with zero debt.” It said “demand already exists,” citing buyer
indications of 12.7 times what the company exported. It described the floor
price as “a compelling entry point.” In a footnote, it said the demand figure
consisted of “non binding letters of intent and demand inquiries.”
The questions were asked before the money was
The concerns were raised in public before approval. When the
draft prospectus was put out for comment from August 5 to 12, a CFA Charter holder filed
twelve questions. They included the gap between FY26 profit of PKR 303.82
million and operating cash flow of PKR 3.74 million, the PKR 281.7 million sale
to the predecessor partnership, Shaheen Enterprises, and whether a single
company audit opinion was being presented as a three-year clean record.
The CTIs answered every point. They said 61.2% of the
June-end receivables had been recovered by July 31, that the sale to Shaheen
Enterprises was a “transitional arrangement” that would not recur, and they
revised the audit-opinion wording. Each response letter closed with the same
line: “Looking forward to your investment in the IPO of SE Fruit &
Vegetable Limited.”
What Mettis flagged before the IPO
On September 19, before book building opened, Mettis Global
set out the same pressure points after putting them to SEFL’s CFO.
We reported that operating cash flow had fallen to about 1.2% of net income in FY26, from 81.5% in FY24, and that receivables had jumped from PKR 212.6 million to PKR 995.9 million. We noted that five of the ten largest FY26 customers had no recorded sales in the prior two years, and that one of them was Shaheen Enterprises itself, at 13.2% of revenue.
Supplier
concentration had risen from 26.5% to 72.8% in a year. Mango and potato were
sourced entirely through middlemen, despite the company being described as
“vertically integrated.” Cash balances in the projections also failed to
reconcile between footnote and the statements, by PKR 94.8 million in FY27 and PKR
150.8 million in FY31.
The CFO told Mettis that more than 97% of receivables had
been collected by September 18. We reported that figure as company-reported and
not independently verified. Our conclusion was that the investment case rested
on execution, and that investors were “being asked to bridge a real gap.”
What investors need now
The company, the lead managers, PSX and SECP have not
answered three questions:
- When
will investors receive either shares or their money?
- Has
PSX extended the listing-permission deadline beyond October 20?
- Will
the 2% surcharge apply if refunds become due and are delayed?
The firms that vouched in writing for every word of the prospectus can now vouch for one more thing: what happens to investors’ money, and when.
Copyright Mettis Link News
Related News
| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 165,552.08 40.40M | 0.26% 427.67 |
| ALLSHR | 100,323.47 184.35M | 0.17% 165.78 |
| KSE30 | 49,123.89 22.20M | 0.24% 119.73 |
| KMI30 | 238,643.53 14.16M | 0.35% 829.56 |
| KMIALLSHR | 65,068.72 80.21M | 0.29% 185.96 |
| BKTi | 45,675.42 4.79M | 0.34% 153.43 |
| OGTi | 33,591.32 0.98M | 0.10% 33.29 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 83,810.00 | 84,025.00 81,070.00 | 885.00 1.07% |
| BRENT CRUDE | 105.37 | 106.14 105.00 | -1.28 -1.20% |
| RICHARDS BAY COAL MONTHLY | 128.50 | 0.00 0.00 | 1.00 0.78% |
| ROTTERDAM COAL MONTHLY | 144.75 | 0.00 0.00 | -0.05 -0.03% |
| USD RBD PALM OLEIN | 1,167.50 | 1,167.50 1,167.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 92.46 | 93.49 92.17 | -1.28 -1.37% |
| SUGAR #11 WORLD | 20.86 | 20.89 20.00 | 0.61 3.01% |
Chart of the Day
Latest News
Top 5 things to watch in this week
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|