Inflation projected at 10.5% in October FY27
MG News | October 29, 2026 at 07:47 PM GMT+05:00

October 29, 2026 (MLN): Inflation is projected in
the range of 9.5-10.5% for October 2026, with the subsequent path sensitive to
international energy prices, food supplies and base effects, even as Pakistan’s
economy consolidates macroeconomic stability in the first quarter of FY2027.
The near-term trajectory remains supported by improved
external financing, better Kharif harvests, and strong automobile and cement
activity, according to the Finance Division’s Monthly Economic Update and
Outlook for October 2026.
The division flagged geopolitical tensions, recurring
conflict in the Gulf region, volatile oil prices, trade disruptions and
elevated global inflation as the main downside risks to the economy.
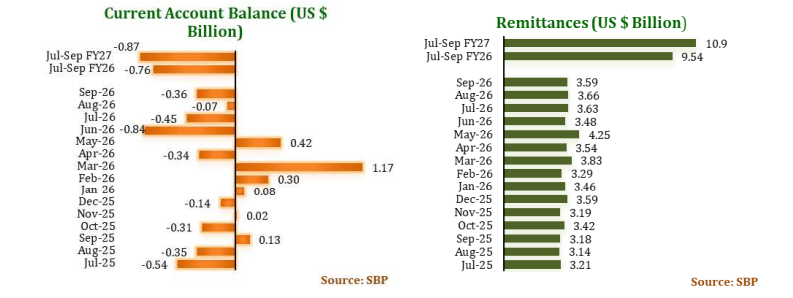
The current account deficit stood at $874mn in Jul-Sep
FY2027, compared with $755mn a year earlier, as import payments rose.
Goods imports grew 14.3% to $17.8bn on higher purchases
of machinery, metals and transport equipment, alongside increased energy costs,
outpacing a 7.7% rise in goods exports to $8.5bn.
Workers’ remittances increased 14.0% to $10.9bn, more than covering the combined goods and services trade deficit.
Food exports rose 25.3%, led by rice, while textile
exports gained 5.3%.
Total foreign investment reached $3.65bn against a net
outflow of $32.9mn a year earlier, with portfolio investment recording net
inflows of $2.9bn compared with net outflows of $633.3mn. FDI rose about 20% to
$720mn.
A $3.0bn sovereign Eurobond issuance in September was
central to the improvement, helping deliver a balance of payments surplus of
$3.1bn against a deficit of $274mn in the same quarter last year.
SBP’s liquid reserves stood at $21.5bn on October 16,
while total liquid reserves were $26.8bn. The rupee stood at Rs276.8/$ on
October 28 against Rs280.97/$ a year earlier.
On the fiscal side, FBR tax collection grew 7.0% to
Rs3,086.2bn in Jul-Sep FY2027, exceeding the target by Rs33.2bn. Sales tax rose
11.6%, federal excise duty 3.6% and customs duties 0.5%, while direct taxes
grew 5.5%.
The overall fiscal surplus narrowed to Rs1,197.9bn (0.8%
of GDP) in Jul-Aug from Rs2,123.8bn (1.7% of GDP) a year earlier, as mark-up
payments rose 36.6% and development expenditure surged 69.5%.
The primary surplus stood at Rs2,311.2bn (1.6% of GDP),
against Rs2,938.9bn (2.3% of GDP) last year.
Total expenditure increased 20.7%, while non-interest
expenditure fell 8.1% on a 90.0% cut in subsidies.
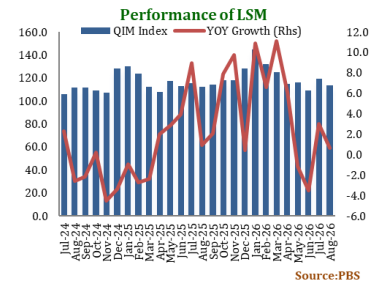
Large-Scale Manufacturing grew 1.9% in Jul-Aug FY2027, compared with 4.8% a year earlier. In August, output rose 0.7% YoY but fell 5.0% from July, with lower production in food, chemicals and pharmaceuticals weighing on the monthly result.
During Jul-Sep, truck and bus production rose 54.2%, car
production 31.8% and two- and three-wheeler production 28.1%. Jeep and pickup
production gained 1.2%, while tractor production fell 15.3%.
Cement dispatches rose 3.9% to 13.1mn tonnes. Domestic
dispatches gained 7.8% to 10.8mn tonnes, offsetting an 11.3% fall in exports to
2.3mn tonnes.
Kharif 2026 delivered strong results for most major
crops. Maize production is estimated at 9.98mn tonnes, up 12.1%, sugarcane at
97.3mn tonnes, up 8.8%, and rice at 10.2mn tonnes, up 1.8%. Cotton output
declined 4.8% to 6.71mn bales.
Agricultural credit disbursements rose 32.7% to
Rs540.5bn in Jul-Aug, from Rs407.2bn a year earlier. Urea offtake rose 8.4% to
3,366 thousand tonnes during Kharif 2026 (Apr-Sep), while DAP offtake fell 25.4%
to 485 thousand tonnes. Tractor sales increased 37.8% to 4,109 units in
Jul-Sep.
The government has fixed the wheat price at Rs4,500 per
maund for Rabi 2026-27.
Revised national accounts placed FY2026 real GDP growth
at 3.65%, marginally below the earlier estimate of 3.70%. Agriculture was
revised up to 3.50% from 2.89%, while industry and services grew 3.34% and 3.81%,
respectively.
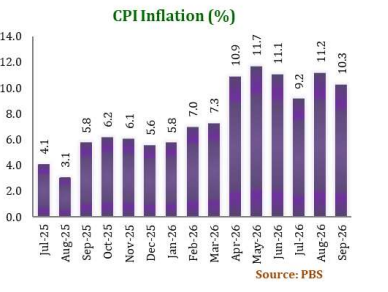
Headline CPI inflation eased to 10.3% YoY in September from 11.1% in August, compared with 5.8% a year earlier, bringing the Jul-Sep average to 10.2% against 4.3% last year.
Transport prices rose 27.4% YoY, while housing, water,
electricity, gas and fuel prices gained 12.4%. Perishable and non-perishable
food prices rose 11.8% and 7.6%, respectively.
The Sensitive Price Indicator increased 0.65% in the
week ended October 22, with prices rising for 19 items, falling for 12 and
remaining unchanged for 20.
The Monetary Policy Committee raised the policy rate by
50bps to 12.0%, citing inflationary risks from the intensifying Middle East
conflict and persistently high global energy prices. The decision aims to
anchor inflation expectations, contain second-round effects and keep inflation
within the target range.
Broad money (M2) contracted 3.9% between July 1 and
October 16, against a 2.5% contraction a year earlier. Net domestic assets
declined by Rs2,360.3bn, more than offsetting a Rs537.5bn increase in net
foreign assets.
Net retirement of government borrowing for budgetary
support stood at Rs2,571.8bn, compared with Rs1,822.9bn a year earlier. Of
this, Rs1,873.9bn was from scheduled banks and Rs697.9bn from the SBP.
Private sector credit recorded net borrowing of Rs5.7bn
against a net retirement of Rs21.1bn a year earlier, with the outstanding stock
about 15.0% higher YoY. Demand is expected to rise further with the arrival of
cash crops.
The KSE-100 fell 7,006 points in September to close at
169,969, while market capitalization declined Rs903bn to Rs18,928bn, as higher
energy costs weighed on earnings expectations and the interest rate outlook.
The index stood at 165,736 on October 28, up 3.52% from a year earlier.
Globally, the IMF’s October World Economic Outlook
projects growth of 3.1% in 2026 and 3.4% in 2027, with global headline
inflation rising to 4.7% in 2026 before easing to 4.1% in 2027. The J.P. Morgan
Global Composite PMI rose to 54.3 in September from 53.5.
Brent crude averaged $116.8 per barrel in September, up
28.4% from August. The FAO Food Price Index rose 1.5% to 136.0 points.
Overall, while higher energy prices and geopolitical
tensions remain key risks, resilient remittances, a stronger reserve position,
renewed access to international capital markets, better harvests and strong
automobile and construction activity position Pakistan to sustain the recovery
while consolidating stability.
The government said it remains committed to anchoring
inflation expectations and reinforcing fiscal and external resilience, with
targeted fuel subsidies cushioning vulnerable households and structural reforms
supporting investment and productivity.
Copyright Mettis Link News
Related News
| Name | Price/Vol | %Chg/NChg |
|---|---|---|
| KSE100 | 167,193.44 366.12M | 0.88% 1456.68 |
| ALLSHR | 101,164.95 815.04M | 0.80% 806.11 |
| KSE30 | 49,320.68 134.37M | 0.99% 482.30 |
| KMI30 | 238,958.16 110.19M | 0.84% 2000.56 |
| KMIALLSHR | 65,336.06 481.98M | 0.82% 528.42 |
| BKTi | 46,284.55 24.74M | 0.99% 454.81 |
| OGTi | 33,773.06 6.87M | 0.71% 237.97 |
| Symbol | Bid/Ask | High/Low |
|---|
| Name | Last | High/Low | Chg/%Chg |
|---|---|---|---|
| BITCOIN FUTURES | 81,195.00 | 81,500.00 79,565.00 | -330.00 -0.40% |
| BRENT CRUDE | 113.52 | 114.94 112.89 | -1.80 -1.56% |
| RICHARDS BAY COAL MONTHLY | 128.50 | 0.00 0.00 | 0.25 0.19% |
| ROTTERDAM COAL MONTHLY | 145.70 | 145.70 145.60 | -0.15 -0.10% |
| USD RBD PALM OLEIN | 1,182.50 | 1,182.50 1,182.50 | 0.00 0.00% |
| CRUDE OIL - WTI | 100.35 | 102.31 99.79 | -2.43 -2.36% |
| SUGAR #11 WORLD | 19.48 | 19.80 19.34 | 0.14 0.72% |
Chart of the Day
Latest News
Top 5 things to watch in this week
 MTB Auction
Pakistan Stock Movers
| Name | Last | Chg/%Chg |
|---|
| Name | Last | Chg/%Chg |
|---|